Table of Contents
What Is Happening in Russia
News from Russia has revived an uncomfortable memory of the early pandemic years. As of October 8, 2026, Russian authorities continue to say there is no plague outbreak in the Irkutsk region and have rejected reports of a second case. Reuters reported that Russia’s health regulator says there is no epidemic risk, while the World Health Organization is still seeking more information about the death of the laboratory worker and says it does not yet have enough detail to determine exactly what caused her illness.
That raises a practical question for Canadian banking: if customers and employees suddenly could not operate normally again, what did the financial system learn from the Pandemic?
Branch Operations Changed
In 2020, banks reduced branch hours, temporarily closed locations and moved large numbers of employees to work from home. The Financial Consumer Agency of Canada (FCAC) reported that some institutions temporarily closed close to 40% of their branches, while others closed fewer than 5%. Most services had to continue through online, mobile, telephone and ATM channels.
That shift exposed a weakness at the same time it demonstrated resilience. FCAC later found that almost one-third of Canadians surveyed in 2020–2021 experienced challenges related to branch closures. In other words, digital banking worked for many people, but not equally well for everyone.
Digital Banking as Default
Online banking and contactless payments already existed before COVID. The pandemic did not invent them; it accelerated their use. Payments Canada found that electronic payments represented 79% of all transactions in 2020, contactless payment volume rose 13%, and most card networks increased contactless transaction limits from $100 to $250. E-commerce transaction value also grew 20%.
By late 2020, 44% of Canadians surveyed said COVID had changed their payment preferences toward digital and contactless for the long term. That is one of the clearest signs that the pandemic changed behaviour, not merely temporary bank operating hours.
Mortgage Relief Changed Fast
The most obvious policy response for homeowners was mortgage payment relief. In March 2020, Canada’s major banks committed to case-by-case help that could include deferrals up to six months. Relief was also offered on other credit products. At the peak in June 2020, CMHC reported that 16.7% of Canada’s outstanding mortgage balance was in deferral.
That six-month program was an emergency measure, not a permanent right. Today, FCAC still describes mortgage deferrals, generally for a shorter period and based on the borrower’s circumstances. The lasting lesson is less “everyone gets a six-month deferral” and more “contact the lender early when hardship begins.” That is the same reason I emphasize acting before a missed payment in I Lost My Job. What Happens to My Mortgage?
Deferrals can also affect the total cost of a mortgage because unpaid amounts still have to be dealt with later. Depending on the solution, payments or amortization may change. My comparison of 25-year versus 30-year amortization explains why extending repayment can reduce a monthly payment while increasing long-term interest.
Mortgage Approval
The pandemic also changed mortgage risk policy, although some changes were short-lived. CMHC says it introduced temporary mortgage-insurance underwriting changes in 2020 because of pandemic-driven economic uncertainty, then returned to its earlier approach. That is important: the pandemic did not permanently rewrite every mortgage qualification rule.
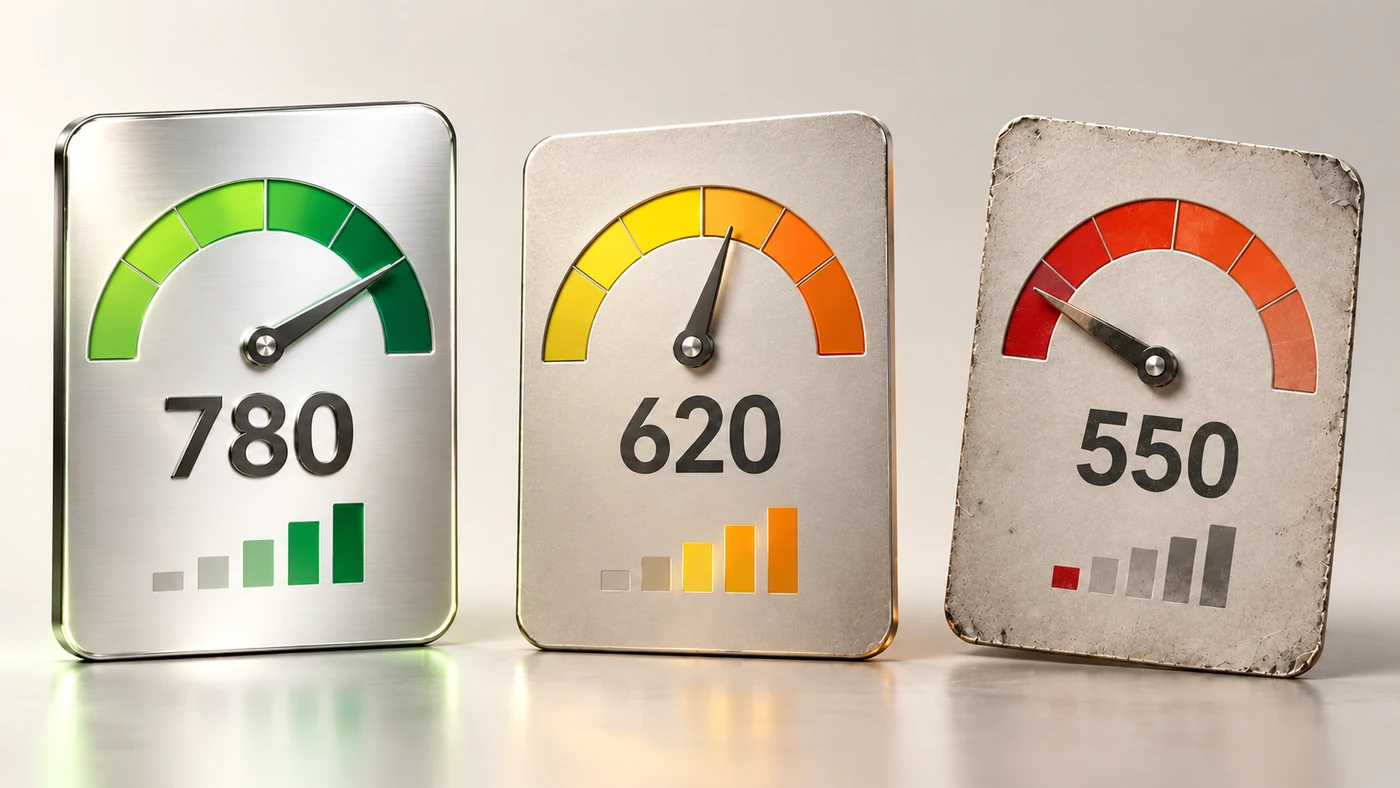
But it demonstrated how quickly employment, income and credit risk can change. Those are still central to how lenders look at a file. Also check out my article How Does Your Credit Score Affect Your Mortgage?. For insured borrowers, the interaction between income, debt ratios and mortgage insurance is also why high-ratio mortgages can involve stricter qualification rules.
Remote Identity Verification
One practical consequence of remote finance is that a customer does not always have to stand across a desk from someone to prove who they are. Current FINTRAC guidance allows government-issued photo identification to be verified when the person is not physically present, provided the institution has a process that can authenticate the document. Credit-file and dual-process methods can also be used in appropriate circumstances.
That should not be described as a rule created solely by the pandemic. Remote identification was part of a broader move toward digital financial services. The pandemic simply made the need for reliable non-face-to-face processes much more obvious. The trade-off is that digital convenience creates additional fraud and cybersecurity risk, which is why issues related to mortgage fraud matter even more in a remote environment.
How Banks Plan for Disruption
This may be the pandemic’s most important institutional legacy. OSFI said the sudden move to remote work put pressure on banks’ operations, technology, staff, processes, controls and suppliers, even though critical banking operations continued without major disruption. That experience became part of a much larger focus on operational resilience.
Today, OSFI’s operational resilience guideline specifically includes health pandemics among the severe scenarios financial institutions should consider when testing their ability to keep critical operations running. OSFI also introduced stronger technology and cyber-risk expectations through Guideline B-13.
What Pandemic Changes Still Remain?
The temporary pieces were the easiest to see: six-month deferrals, emergency relief programs, branch restrictions and temporary underwriting changes. Most of those ended or were revised. The lasting changes are more structural: customers became more comfortable banking remotely, institutions built stronger remote workflows, contactless and online payments moved further into the mainstream, and regulators put greater weight on technology, cybersecurity and continuity planning.
Mortgage qualification itself did not become permanently “virtual” in the sense of becoming easier. Borrowers still have to prove income, creditworthiness and acceptable debt ratios, and federally regulated lenders still apply the mortgage stress test. A digital application can make the process more convenient, but it does not remove the underwriting behind it. The same is true for loan-to-value: technology may change how documents reach a lender, not the underlying risk the lender is measuring.
If another health emergency ever restricted movement again, the Canadian banking system would not be starting from the same place it was in March 2020. The infrastructure, customer habits and regulatory expectations for remote operations are all much further developed.
That does not mean every future emergency would produce the same mortgage relief. A new crisis could lead to different lender policies depending on unemployment, credit conditions, government action and the nature of the emergency. Borrowers facing pressure may still need individual solutions, including refinancing or debt consolidation, rather than expecting a repeat of the 2020 deferral program.
The real banking lesson from the pandemic is therefore not that the rules permanently became easier. It is that Canadian banks learned how to keep more of the financial system functioning when customers and employees could not be in the same room.