Mortgage Stress Test
Canada’s mortgage stress test checks whether you can afford a mortgage at a higher qualifying interest rate than the rate you’ll actually pay. For most new mortgages from federally regulated banks, the test uses the greater of 5.25% or your contract rate plus 2 percentage points. The lender then calculates your Gross Debt Service (GDS) and Total Debt Service (TDS) ratios to decide whether your debts fit its lending rules.
Quick answer: GDS measures housing costs as a percentage of gross household income; TDS adds other monthly debt obligations. Under CMHC’s standard insured-mortgage criteria, the limits are generally 39% GDS and 44% TDS. These are qualification thresholds, not a guarantee of affordability or approval.
Table of Contents
In practical mortgage underwriting, alongside measures such as loan-to-value (LTV), the stress test works through two calculations: GDS and TDS.
The lender does not simply look at your mortgage payment at the rate you will actually pay. It calculates a payment using the applicable qualifying rate, then plugs that higher payment into your debt-service ratios, which can reduce how much mortgage you qualify for.
That is why someone can be perfectly comfortable with the real monthly mortgage payment and still fail to qualify for the mortgage.
Qualifying Rate
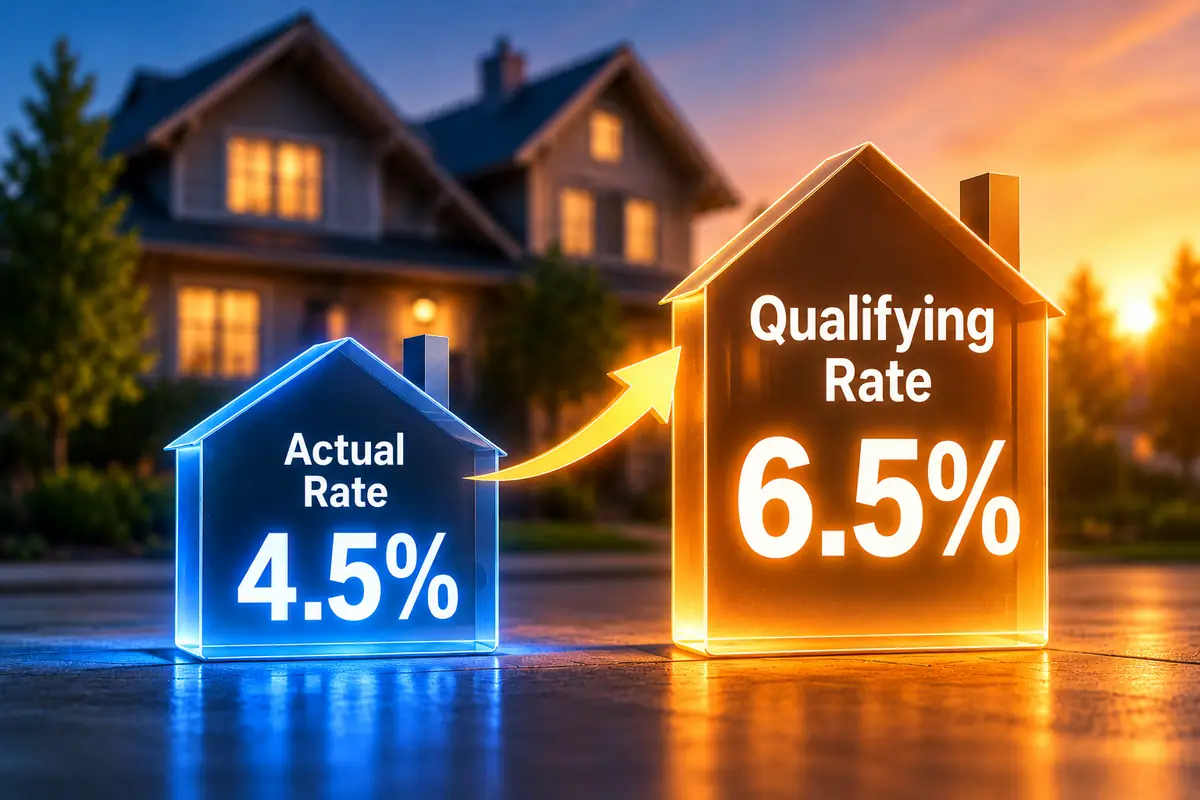
For federally regulated uninsured mortgages, the current minimum qualifying rate is the greater of:
- 5.25%, or
- your mortgage contract rate plus 2 percentage points.
CMHC uses the same greater-of calculation in its insured mortgage programs.
So if your mortgage rate is 4.50%, the lender generally tests the mortgage payment at 6.50%. If your mortgage rate were 2.75%, the 5.25% floor would be higher than 4.75%, so 5.25% would be used.
Source: OSFI — Minimum Qualifying Rate | CMHC — Calculating GDS/TDS
Gross Debt Service (GDS)
GDS stands for Gross Debt Service ratio. It measures how much of your gross income is required to cover the basic carrying costs of the home.
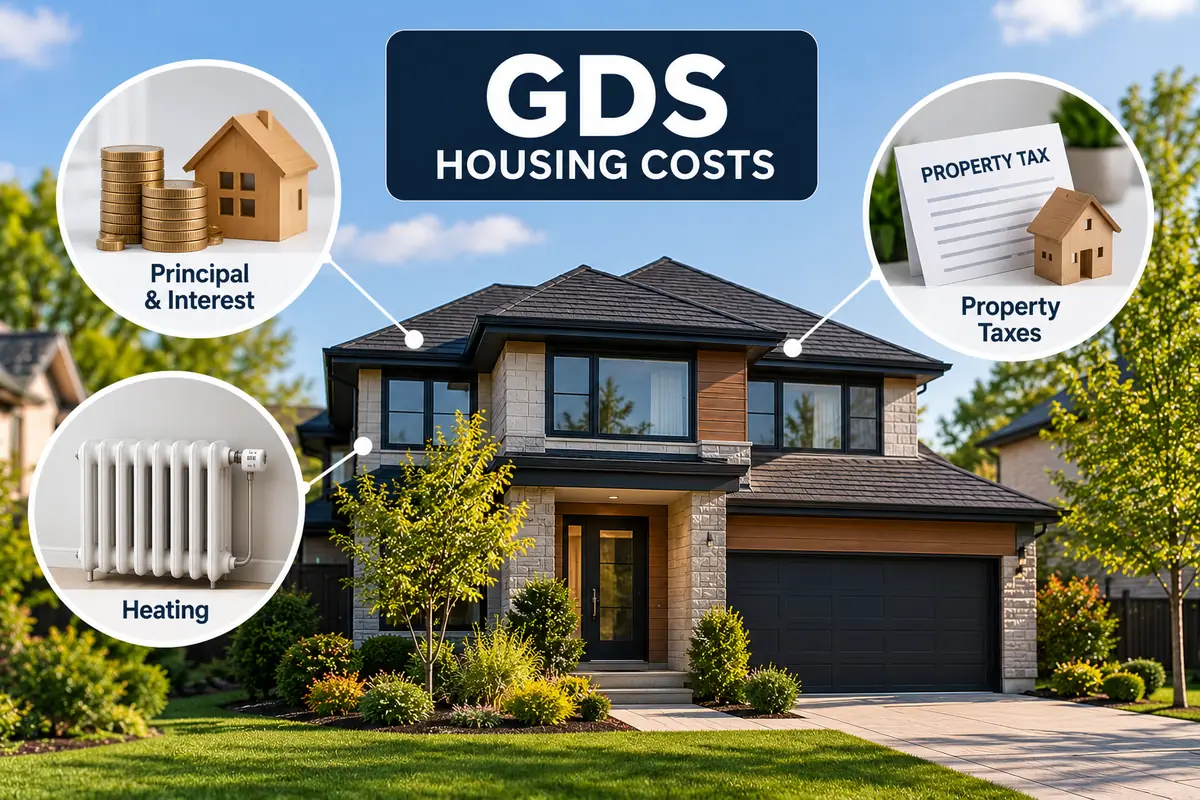
For CMHC-insured mortgages, the standard maximum GDS threshold is 39% under CMHC’s published guidelines. To calculate it, first convert your annual gross household income to monthly income by dividing by 12, then divide the lender’s qualifying monthly housing costs by that monthly income and multiply by 100.
CMHC GDS housing costs include the principal-and-interest mortgage payment calculated at the qualifying rate, property taxes, heating and normally 50% of condominium fees where applicable. Depending on the property, other site or ground rent charges may also count.
For a condominium, 50% of the condo fees are generally included in the CMHC GDS calculation. Property taxes and heating costs also count even though they are not part of the mortgage payment itself.
This is one reason two people asking for the exact same mortgage amount can qualify differently. A property with high taxes or high condo fees can produce a higher GDS even when the mortgage itself is identical.
Total Debt Service (TDS)
TDS stands for Total Debt Service ratio. It starts with the housing costs used in GDS and then adds the borrower’s other debt obligations.
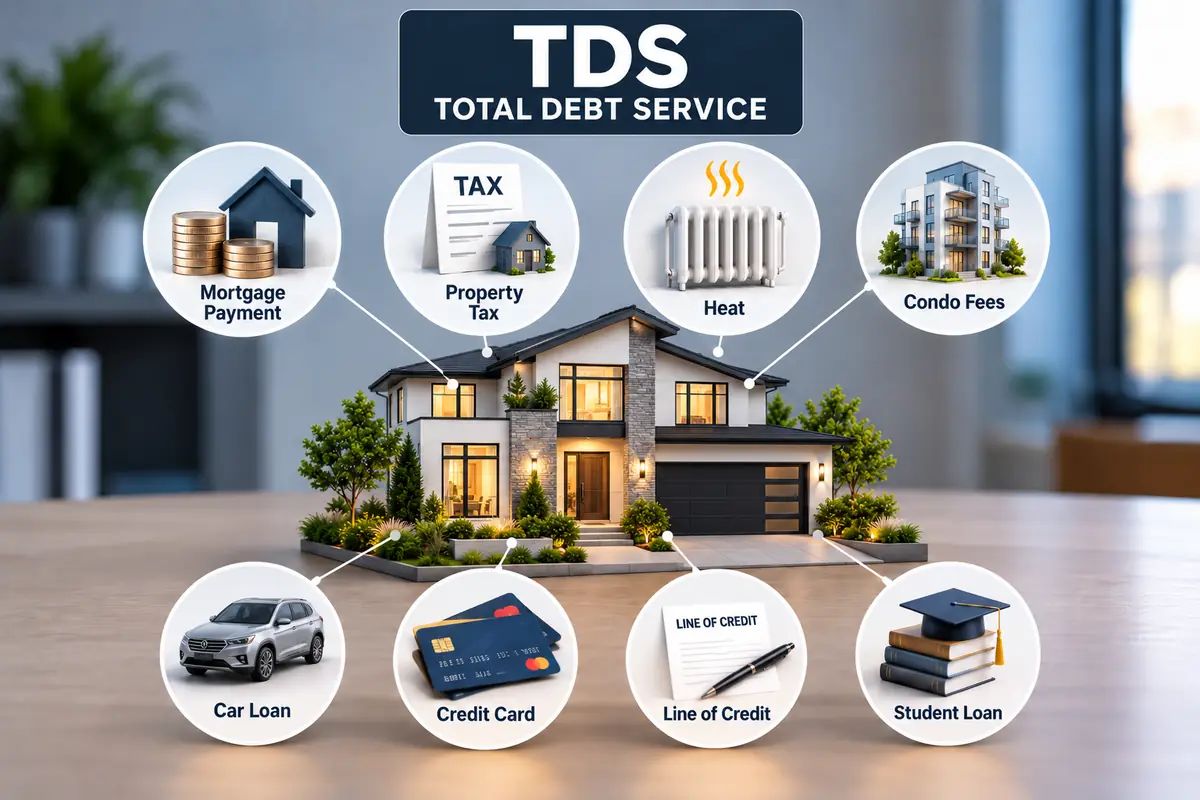
For CMHC-insured mortgages, the standard maximum TDS threshold is 44% under CMHC’s published guidelines. Calculate TDS by adding your other qualifying monthly debt obligations to the same housing costs used in GDS, dividing by monthly gross household income and multiplying by 100. Credit cards and lines of credit can be assessed using a required payment amount determined by the lender or mortgage insurer rather than simply your latest minimum payment.
Depending on the lender and the debt, TDS can include obligations such as:
- car loans or leases
- credit-card obligations
- lines of credit
- personal loans
- student loans
- support payments and other recurring obligations
The exact treatment of a particular debt can vary by lender and mortgage program. For example, some lenders assess a minimum monthly obligation based on an outstanding revolving-credit balance rather than relying only on a payment shown on a statement. CMHC explains the inputs used to calculate GDS and TDS.
Source: Financial Consumer Agency of Canada — Preparing to Get a Mortgage | FSRA — Mortgage Application Process
Mortgage Stress Test Example
This is the part that causes the most confusion.
Suppose a household earns $100,000 per year, or about $8,333 per month before tax.
They want a $400,000 mortgage amortized over 25 years at 4.50%. The actual mortgage payment is roughly $2,214 per month. But if the qualifying rate is 6.50%, the payment used for the stress test is roughly $2,679 per month.
Assume the property also has $400 per month in property taxes and $150 per month in heating costs.
That borrower is just under the 39% CMHC GDS threshold.
Now suppose the borrower also has a $400 monthly car payment and another $150 per month of qualifying debt obligations. Those debts do not change the GDS — but they do change the TDS.
Here is the complete calculation:
- Gross monthly household income: $100,000 ÷ 12 = approximately $8,333.
- GDS housing costs: $2,679 qualifying mortgage payment + $400 property tax + $150 heat = $3,229.
- GDS: $3,229 ÷ $8,333 × 100 = 38.8%, just under CMHC’s 39% standard maximum.
- TDS: ($3,229 housing costs + $400 car payment + $150 other debt) ÷ $8,333 × 100 = 45.4%, above CMHC’s 44% standard maximum.
So this borrower is under the GDS limit but over the TDS limit. Passing one ratio does not mean you pass both.
How Do Condo Fees Affect GDS and TDS?
Suppose gross household income is $120,000 annually ($10,000 monthly). The qualifying mortgage payment is $2,800, property taxes are $400 per month, heat is $150 and condo fees are $500. Under CMHC’s standard method, half the condo fees ($250) are counted. GDS = ($2,800 + $400 + $150 + $250) ÷ $10,000 × 100 = 36%. If the borrower also has $900 in qualifying monthly car-loan and other debt obligations, TDS = ($3,600 + $900) ÷ $10,000 × 100 = 45%, exceeding CMHC’s standard TDS limit.
This is why paying off a car loan or reducing another debt can sometimes make a surprisingly large difference to mortgage qualification even though nothing about the house has changed.
How to Calculate GDS and TDS Before Applying
You can estimate your GDS and TDS ratios before speaking to a lender. Use the mortgage payment calculated at the stress-test qualifying rate, not just the lower payment you would make at your contract rate.
- Find your gross monthly household income: divide your eligible annual gross income by 12.
- Estimate the qualifying mortgage payment: first calculate the mortgage payment using the greater of 5.25% or your offered rate plus two percentage points, where that minimum qualifying rate applies. You can try my mortgage payment calculator, entering the qualifying rate for this estimate.
- Add the housing expenses: property taxes, heat and the applicable portion of condo fees or other charges. Divide this total by gross monthly income and multiply by 100 to find GDS.
- Add other qualifying monthly debts: car loans, credit cards, lines of credit and other required obligations. Divide all housing and qualifying debt expenses by gross monthly income and multiply by 100 to find TDS.
- Compare your results: CMHC’s standard insured-mortgage thresholds are 39% GDS and 44% TDS. Lenders may apply different limits, debt-payment assumptions or additional conditions.
Prefer an interactive worksheet? Use the official CMHC GDS/TDS debt-service calculator. Enter your stress-tested mortgage payment into its monthly mortgage payment field if you want to estimate qualification under the higher interest rate. The CMHC tool does not by itself establish whether your individual lender will approve your application.
Understanding Your Budget
Debt-service ratios are underwriting calculations. They are not a complete household budget.
Groceries, childcare, transportation, insurance, cell-phone bills and many other everyday costs are generally not included in the simple GDS/TDS formulas in the same way that mortgage payments and debt obligations are.
FSRA specifically cautions that qualifying under debt-service ratios does not necessarily mean a mortgage is affordable for a particular household. Your actual monthly budget may tell a different story.
How Higher Rates Affect Qualification
The stress test does not directly reduce your income. When mortgage rates rise, it increases the mortgage payment that the lender uses in the qualification calculation.
A higher qualifying payment pushes GDS and TDS upward. Once one of those ratios becomes too high for the lender or mortgage program, the requested mortgage may no longer fit.
This creates an important relationship: as the qualifying mortgage payment increases, both debt-service ratios rise, potentially reducing the mortgage amount a borrower can qualify for—even when income and other debts stay the same.
The reverse can also happen. Lower debt obligations, more qualifying income, a smaller mortgage, lower property taxes or lower condo fees can reduce the ratios.
Refinancing and the Stress Test
The stress test can be especially important when refinancing a mortgage.
A homeowner may have plenty of equity according to the property’s loan-to-value ratio (LTV), but equity alone does not necessarily mean the borrower qualifies for the mortgage amount requested.
The lender can still ask whether the borrower’s income supports the new mortgage payment after applying its qualifying rate and debt-service calculations.
This is particularly important when someone is refinancing for debt consolidation. Paying off outside debt with the refinance may improve the final TDS calculation, but the lender still has to determine which debts are being paid, how they will be treated and whether the new mortgage fits its underwriting rules.
Mortgage Renewals
The stress-test rules have an important renewal exception.
OSFI no longer prescribes the minimum qualifying rate for certain uninsured straight switches from one federally regulated lender to another at renewal when there is no increase in the loan amount or remaining amortization period.
There are also rules allowing qualifying insured borrowers to switch lenders at renewal without being required under the federal mortgage-insurance rules to requalify using the minimum qualifying rate.
That means a borrower should not assume that simply changing lenders at renewal automatically requires the same prescribed stress test that would apply to a new mortgage or refinance. A straight-switch exemption does not guarantee approval: the new lender still assesses the borrower, the property and its own underwriting criteria. Refinancing for extra money or extending the remaining amortization can change which rules apply.
Source: OSFI — Uninsured Mortgage Straight Switches | Department of Finance Canada — Straight Switches and Portfolio Insurance
What Matters Most
People often begin a mortgage conversation by asking:
“What interest rate can I get?”
But the rate you receive and the rate used to qualify you may be different.
For qualification, the more useful questions are:
“What payment will the lender use for the stress test, and what will my GDS and TDS be after that payment is included?”
Those numbers can determine how much mortgage you qualify for long before the first real mortgage payment is ever made. If you are near or over a lender’s limits, compare options such as a smaller mortgage, paying down qualifying debts or adding eligible income before committing to a purchase. An approved debt-service ratio alone does not guarantee that the lender will approve the property or your credit application.
About the author: Jason Wodlinger is an Ontario Mortgage Agent Level 2. This article explains general Canadian mortgage qualification rules; individual lenders may apply additional underwriting policies and exceptions.