What Is LTV?
The loan-to-value ratio, usually called LTV, measures how much mortgage debt is secured against a property compared with the property value the lender accepts.
In simple terms, LTV asks one question: How much debt are you taking on relative to the value of the property the lender is prepared to use?
Quick answer: Loan-to-value (LTV) = total mortgage debt ÷ lender-accepted property value × 100. The result is a percentage: the higher the percentage, the more of the property’s value is being financed with debt.
Why Lenders Care
Lenders care about LTV because the property is their security for the mortgage.
If the borrower stops making payments and the mortgage eventually reaches power of sale, a lower LTV gives the lender a larger equity cushion. A 50% LTV mortgage gives the lender much more room than a 90% LTV mortgage if the property has to be sold quickly or its value falls.
For federally regulated banks, uninsured residential mortgage lending is generally limited to 80% of the accepted property value. Eligible insured home purchases can exceed 80% LTV—up to 95% in some qualifying situations—but insurance and lender rules still apply. This is different from refinancing a mortgage, where an ordinary uninsured bank refinance is generally limited to 80% LTV. Learn more about high-ratio mortgages and down payments below 20%.
Source: Government of Canada — Bank Act | CMHC — Purchase
How LTV Is Calculated
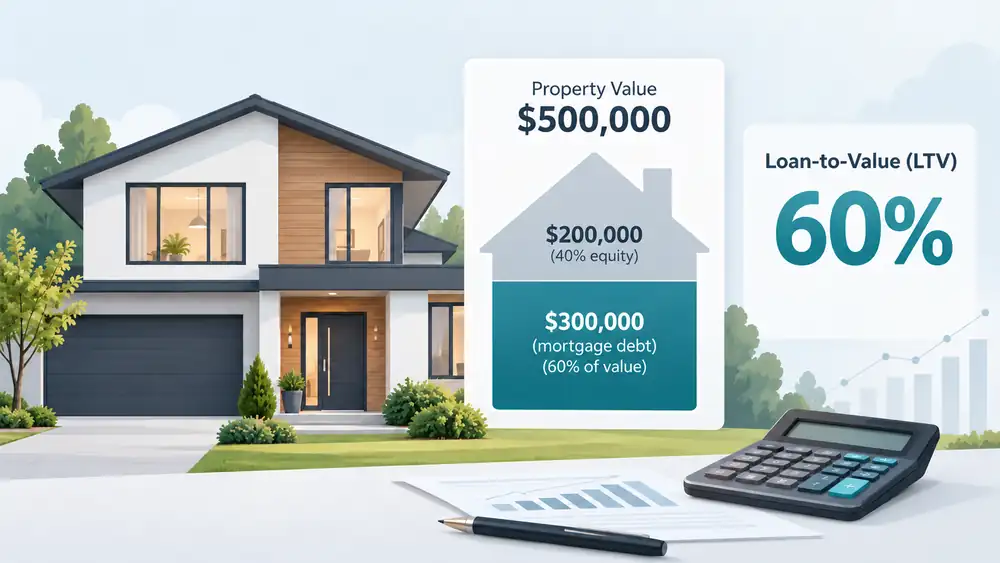
The basic calculation is:
÷
Lender-Accepted Property Value
× 100 = LTV
How to figure loan-to-value in four steps:
- Find the property value the lender will accept, which may differ from your own estimate or the purchase price.
- Identify the secured debt. Include the existing mortgage and any second mortgage that must be counted. For some mortgage/HELOC products, the lender may count authorized credit limits as well as amounts drawn.
- Divide the debt by the accepted property value.
- Multiply by 100 to turn the result into an LTV percentage.
Example: If a lender accepts a property value of $800,000 and the mortgage debt counted is $480,000, the calculation is $480,000 ÷ $800,000 × 100 = 60% LTV. That’s approximately 40% equity before transaction costs and other claims.
If there is a $400,000 first mortgage and an $80,000 second mortgage, the total debt secured against the property is still $480,000. The combined LTV is therefore still 60%.
Next, estimate the payments: Once you’ve calculated the mortgage amount, you can use my mortgage payment calculator to estimate monthly payments. The payment calculator does not calculate your LTV; use the formula above to find that percentage first.
Urban vs. Rural LTV
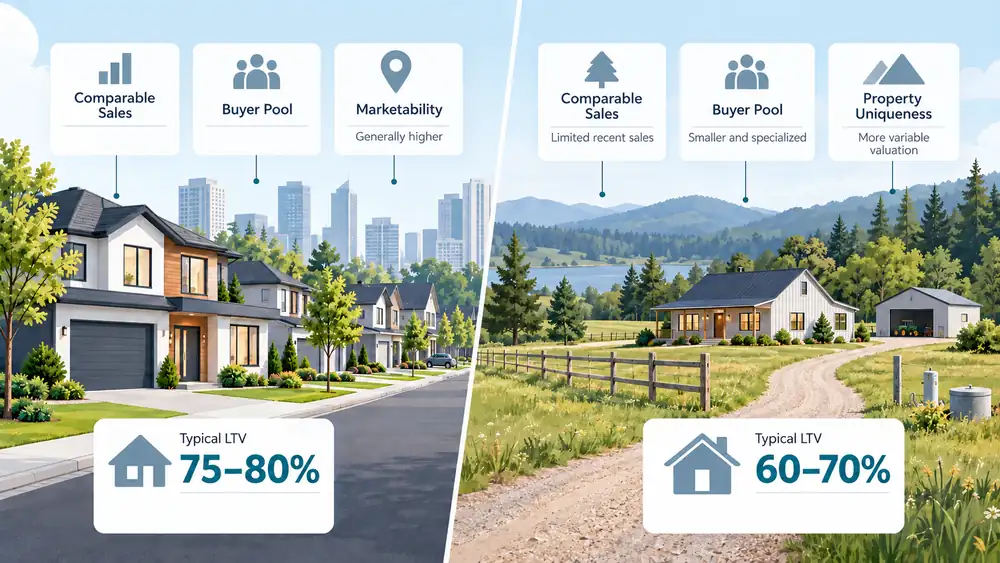
There is no universal rule that says every rural property automatically receives a lower maximum LTV. But lenders care about how easily a property can be valued and how easily it could be sold if they ever had to recover their money.
A typical house in a large urban market may have many recent comparable sales nearby. There may also be a larger pool of potential buyers and a shorter expected marketing time.
Refinancing a rural property in Ontario can sometimes be more difficult because the lender may have to consider issues such as:
- fewer recent comparable sales
- larger acreage
- private wells or septic systems
- private or seasonal road access
- outbuildings or agricultural use
- a smaller potential buyer pool
- longer expected selling times
OSFI requires federally regulated lenders to consider valuation and marketability risks when determining the value used for LTV purposes. That helps explain why a lender may be comfortable lending a higher percentage on a very marketable urban home but become more conservative on a unique or remote rural property.
That does not mean every rural property is difficult to finance. A standard rural home near an established community with year-round road access and good comparable sales may be viewed quite differently from a remote or highly specialized property.
Source: OSFI — 2026 Capital Adequacy Requirements | Refinancing a Rural Property in Ontario
Credit Score and LTV
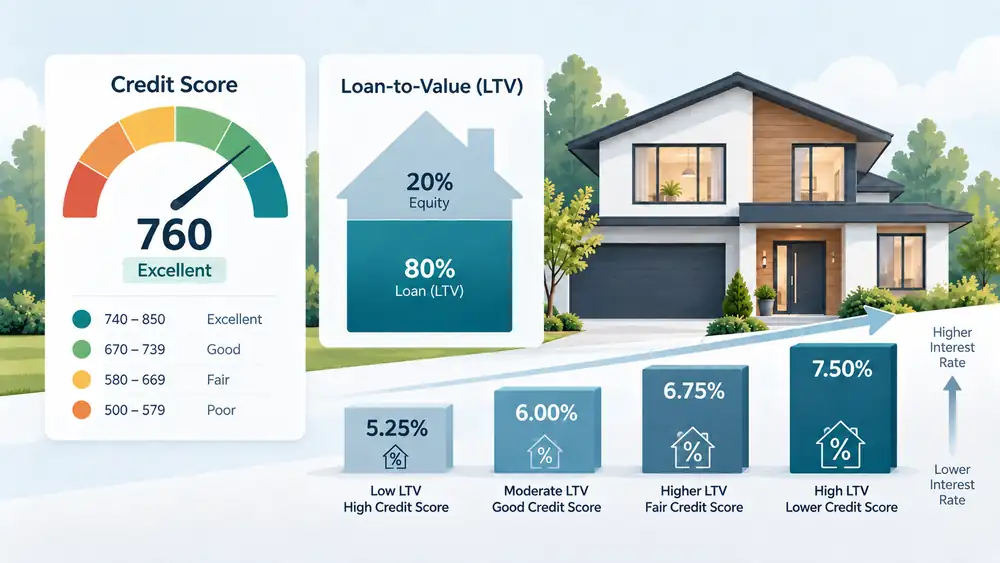
Credit score and LTV measure two different things.
LTV measures the lender’s risk in the property. Credit history helps the lender assess the borrower’s history of repaying debt.
A borrower with an 800 credit score does not automatically get a higher property value or unlimited LTV. But strong credit can give the lender greater confidence in the overall application and can open the door to more lenders and mortgage products.
A borrower with a credit score below 600 may have fewer options. For example, CMHC states that at least one borrower or guarantor must have a minimum credit score of 600 for certain insured mortgage programs.
Private lenders and other alternative lenders may consider borrowers with bruised credit, but they may respond to the additional risk by requiring more equity, limiting the maximum LTV, charging a higher rate or fee, or using some combination of these.
In other words, two borrowers could own identical $800,000 houses and request identical $600,000 mortgages, yet receive different mortgage options because the lender evaluates both the property risk and the borrower risk.
Source: CMHC — Creditworthiness Requirements
LTV and Interest Rates
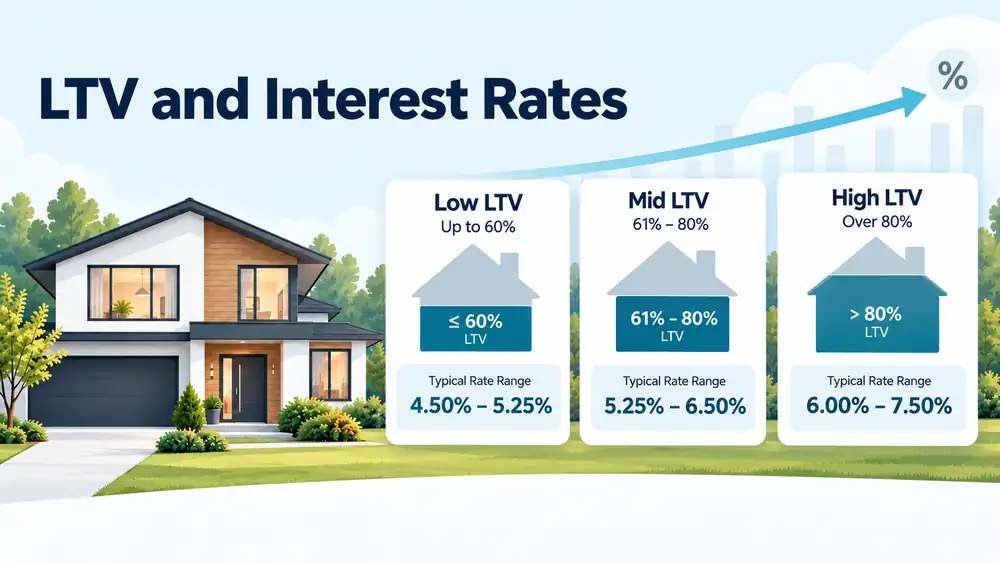
A lower LTV can improve a borrower’s mortgage options, but it does not always produce a lower interest rate.
From a risk perspective, a lower LTV generally gives a lender more protection. This can be especially important with alternative and private lenders, where the amount of equity in the property can have a major influence on the rate, fees and maximum loan amount.
However, mortgage pricing in Canada has an important exception: a high-LTV mortgage that is protected by mortgage default insurance can sometimes receive a very competitive rate — and in some cases a lower rate than an uninsured mortgage — because the insurance protects the lender against certain losses.
At the same time, the cost of mortgage default insurance increases as LTV rises. CMHC’s current premium schedule ranges from 0.60% at the lowest LTV band to 4.00% for many mortgages between 90.01% and 95% LTV, with a higher premium in some non-traditional down-payment situations.
The interest rate therefore cannot be predicted from LTV alone. I explain another key distinction in my guide to 25-year versus 30-year mortgage amortization. Lenders may also consider credit history, income, mortgage type, property, term, whether the mortgage is in first or second position, and other underwriting factors.
Source: CMHC — Mortgage Loan Insurance Costs | Financial Consumer Agency of Canada — Mortgage Interest
How Appraisals Affect LTV
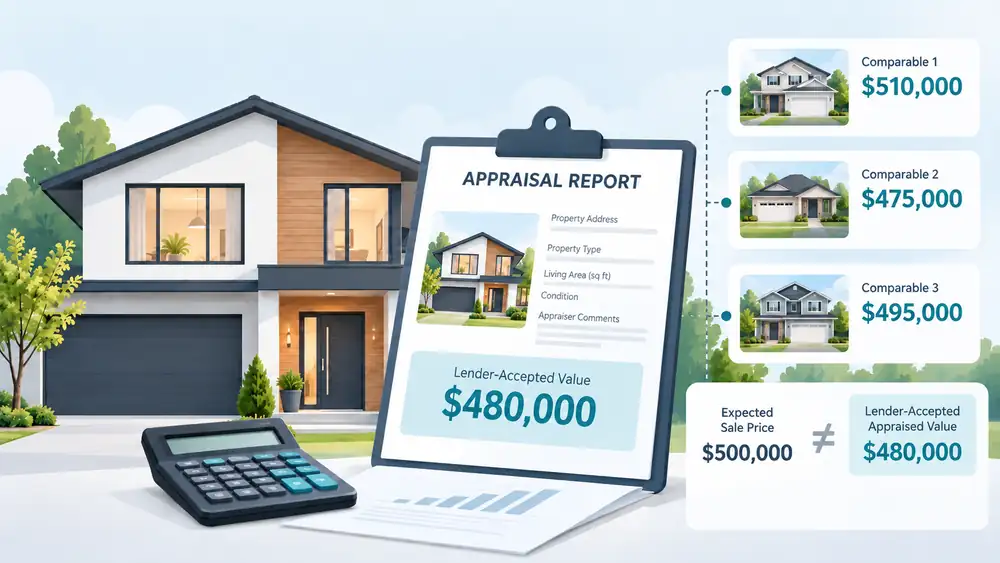
This is where LTV becomes especially important.
A homeowner may believe a house is worth $800,000. A real estate agent may believe it could list for $825,000. A buyer might even be willing to pay $840,000.
But the lender still needs a value it is prepared to use for the mortgage.
An appraisal is an independent professional opinion of market value as of a specific date. Under the Appraisal Institute of Canada’s standards, market value is based on the most probable price a property should achieve after reasonable exposure in a competitive market, with knowledgeable parties acting without undue pressure.
That is not the same thing as guaranteeing what the property will actually sell for. A future sale price can be affected by bidding competition, seller urgency, market changes, unusual financing, property condition and many other factors.
Source: Appraisal Institute of Canada — CUSPAP Market Value Definition
Purchase Price vs. Lender Value
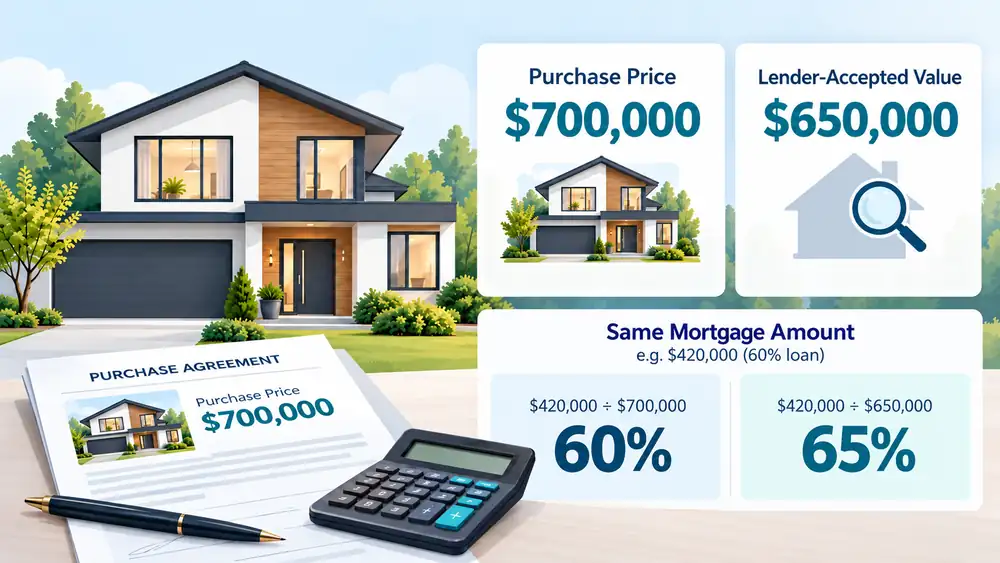
Suppose you agree to buy a house for $700,000 but the accepted lending value is only $650,000.
If you request a $520,000 mortgage, that is not a 74.3% LTV based on the $700,000 purchase price. Against a $650,000 lending value, it is an 80% LTV.
For insured purchase financing, CMHC describes lending value as the lower of the applicable market value and the purchase price or cost in relevant programs. That prevents a borrower from creating extra lending value simply by agreeing to pay more for a property.
Mortgage refinancing is different because there is no new purchase price. The lender therefore relies heavily on the appraisal or other accepted valuation method to determine how much equity actually exists.
For example, if you expected your home to be worth $800,000 and wanted to refinance to 80% LTV, you might expect access to as much as $640,000 of total mortgage debt. If the lender accepts a value of only $700,000, 80% LTV becomes $560,000.
That $100,000 difference in appraised value reduces the 80% lending limit by $80,000.
Source: CMHC — Lending Value and Appraised Value
Who Gets the Appraisal?
This surprises many borrowers.
You may be the person who pays the appraisal fee, but that does not necessarily make you the appraiser’s client.
The Appraisal Institute of Canada explains that, when an appraisal is prepared for mortgage lending, the lender is often the appraiser’s client even though the homeowner pays the fee. The report is prepared for the lender’s lending decision and is subject to confidentiality rules.
According to the AIC, an appraiser may require written authorization from the lender before releasing the appraisal to a third party, including the person who paid for it. The appraiser’s consent may also be required.
So it is more accurate to say that the borrower is not automatically entitled to receive the full appraisal report. It does not mean the borrower can never see it. Some lenders may release the report, part of the report, or the final appraised value depending on their policies and the required authorizations.
If seeing the full appraisal is important to you, ask your mortgage professional or lender about the lender’s policy before ordering and paying for the appraisal.
Source: Appraisal Institute of Canada — Information for Property Owners
Why LTV Can Vary
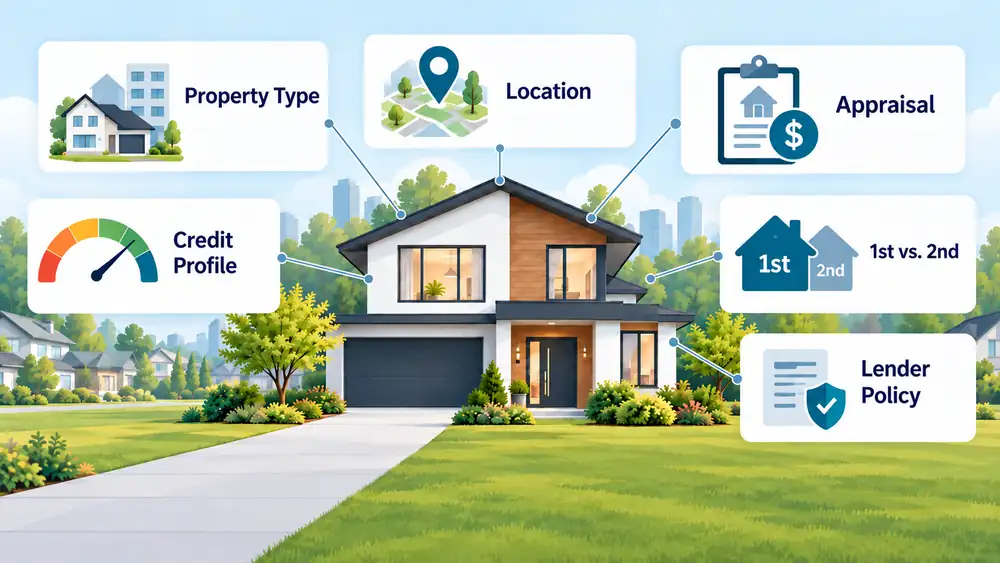
The formula itself is easy. The complicated part is determining what debt the lender will include, what property value the lender will accept and how much risk the lender is willing to take.
A lender may look at the same property differently because of its location, marketability, appraisal, the borrower’s credit profile, the type of mortgage being requested and whether the lender would be in first or second position.
That is why knowing that you have “30% equity” does not automatically tell you what mortgage you will qualify for.
If you are considering taking equity out of your home, refinancing or mortgage refinancing for debt consolidation, the useful question is not simply “What is my house worth?” It is:
“What value will the lender accept, and what maximum LTV will that lender allow for my particular property and application?”
Common Loan-to-Value Questions
What Does 75% LTV Mean?
A 75% loan-to-value ratio means mortgage debt equal to 75% of the property’s accepted value. For example, a $600,000 mortgage on an $800,000 property is 75% LTV, leaving $200,000 of equity on paper before selling costs or other claims.
Is 60% LTV Good for a Mortgage?
A 60% LTV generally means you have substantial equity relative to your mortgage debt, which can give lenders more security and may increase financing options. It does not guarantee the lowest mortgage rate: lenders also consider credit, income, property type, mortgage insurance and other costs.
What Is the Maximum LTV in Canada?
For a conventional, uninsured mortgage from a federally regulated bank, the usual legal limit is 80% LTV. Qualifying insured purchases may allow up to 95% LTV in certain situations. Other lenders and products can have different restrictions; the maximum you can actually obtain depends on approval, the property and the type of transaction. See the Bank Act, section 418.
How Much Equity Can I Borrow When Refinancing?
Suppose your accepted property value is $800,000 and your current mortgage balance is $480,000. At an 80% LTV limit, total secured borrowing would be $640,000. That leaves up to $160,000 in potential additional borrowing before lender approval, fees or penalties. It is a mathematical ceiling, not a preapproval or a promise of available cash.
About the author: Jason Wodlinger is an Ontario Mortgage Agent Level 2. This article explains general Canadian mortgage and LTV concepts; individual lender limits, pricing and qualification requirements vary by borrower, property and mortgage product.