Cryptocurrency is reshaping the mortgage landscape in Canada.
Table of Contents
How Crypto Is Changing Mortgages
FINTRAC is Canada’s financial intelligence unit and anti-money-laundering supervisor. Mortgage-sector reporting entities already have recordkeeping, identity-verification and suspicious-transaction obligations, including rules that address virtual currency. OSFI also published its final 2027 crypto-asset exposure guideline on September 10, 2026. It takes effect November 1, 2026 for institutions with an October 31 fiscal year and January 1, 2027 for institutions with a December 31 fiscal year.
For most borrowers today, getting a mortgage still looks familiar: prove your income, verify your credit, document your down payment, qualify under lender rules and complete the transaction in Canadian dollars. But cryptocurrency is beginning to touch several parts of that process — especially when it comes to source of funds, anti-money-laundering rules, digital payments and the way banks manage crypto exposure.
Crypto: Mortgage Compliance
Cryptocurrency is not just an investment issue anymore. It is now specifically addressed in Canadian mortgage compliance rules. FINTRAC guidance requires mortgage administrators, brokers and lenders to verify the identity of clients in a number of situations, including mortgage loan records and large virtual-currency transactions. If a reporting entity receives virtual currency worth $10,000 or more, specific rules for virtual currency, including identity-verification and reporting requirements, can apply.
FINTRAC also defines source of funds or virtual currency as the actual origin of the money or crypto being used — not simply the account or wallet it came from.
FINTRAC provides guidance for mortgage brokers and lenders, as well as large virtual-currency transactions. That matters because a mortgage application involving crypto may require a more complicated paper trail than a mortgage funded entirely from a traditional bank account.
Crypto as a Down Payment
A borrower may own enough Bitcoin, Ether or another crypto asset to cover a substantial part of a down payment. The harder question is whether the borrower can clearly document where those funds came from and how they arrived in the account being used for closing.
FINTRAC requires mortgage brokers and lenders to maintain records and verify identity in mortgage transactions, and it has specific rules for virtual currency. The CRA also treats selling cryptocurrency for Canadian dollars as a disposition that can have tax consequences.
I could not verify a single public source listing each lender’s policy on cryptocurrency for down payments. So borrowers should check the policy of the specific lender being considered. There is no evidence provinces currently apply different crypto mortgage rules, but separation debates make provincial policy worth watching. If crypto will be converted to cash, be prepared to document the transaction history and source of funds.
Lenders commonly review recent bank or investment statements to confirm down-payment funds, but the exact documentation period varies by lender and mortgage program. If crypto is converted to cash shortly before closing, expect to document the exchange transaction, wallet or platform history and the deposit into the bank account so the lender can trace the funds. If you are putting less than 20% down, mortgage-insurance rules also become part of the approval; see high-ratio mortgages.
Can You Use Crypto as Income?
Crypto can also complicate the income side of a mortgage application.
The CRA says crypto transactions can produce either business income or capital gains depending on the circumstances. Why that matters for a mortgage: lenders qualify borrowers using income they can document and accept, so whether crypto profits are treated as ongoing business income or as investment gains can affect how useful they are in a mortgage application. Selling crypto, exchanging one crypto asset for another, or using crypto to buy goods or services can all create a taxable disposition.
For mortgage qualification, however, the important question is not simply whether you made money from crypto. It is whether the lender considers that income sufficiently documented, stable and likely to continue. If your earnings come from trading, mining, staking, a crypto-related business or another non-traditional source, the lender may need to analyze the income differently from a regular salary. That is the same basic principle discussed in our article on how a bank analyzes your income for a mortgage.
Remember that your down payment is tied to the price of the home, so you may want to consider municipalities where new-home prices have fallen.
Stablecoins versus Bitcoin
Bitcoin gets most of the headlines, but stablecoins may be more relevant to the future mortgage process because they are designed to maintain a stable value rather than fluctuate dramatically. A stablecoin is a type of cryptocurrency designed to stay close to a fixed value, usually by linking itself to a traditional currency such as the Canadian or U.S. dollar. In simple terms, it is meant to behave more like digital cash than an asset whose price can swing sharply.
The Bank of Canada administers Canada’s federal framework for fiat-backed stablecoins and will supervise non-financial institutions that issue them to Canadians. The framework focuses on matters such as backing, redemption and safe issuance. That does not make a stablecoin equivalent to cash for mortgage underwriting; lenders, lawyers and payment systems would still need to accept the particular payment method.
That does not mean lenders are about to start funding mortgages in stablecoins. It means the infrastructure surrounding digital money is becoming more formal and regulated.
How Blockchain Could Affect Mortgages
Blockchain technology can create a tamper-resistant record of transactions. In simple terms, a blockchain is a shared digital record book. Transactions are added in sequence, and the record can be checked across a network instead of relying on one central database. In theory, that could eventually be used to verify parts of a mortgage file — such as the movement of funds, ownership records, digital identity or document history. These issues can matter when buying a home or when refinancing your existing mortgage.
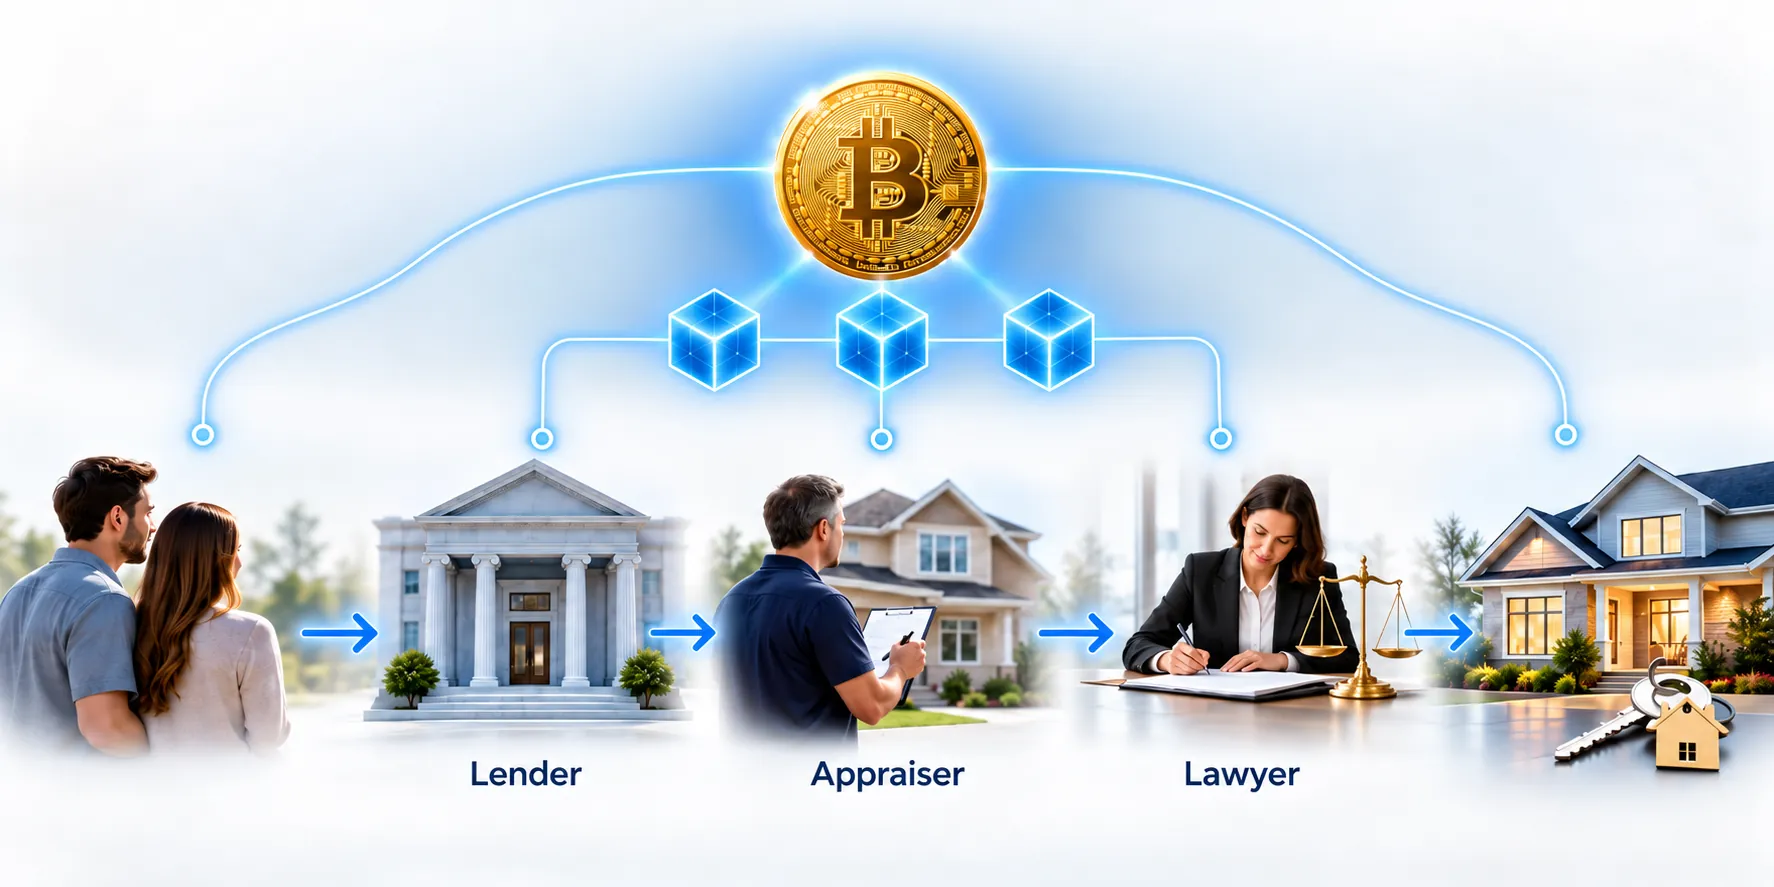
If Canadian lenders, lawyers, land registries and regulators eventually adopt compatible blockchain-based systems, some verification or settlement steps could become easier to audit. That is still speculative. The near-term change is more likely to be improved digital recordkeeping and compliance around the existing mortgage process rather than a completely new crypto mortgage system appearing overnight.
What Probably Will Not Change
Even if cryptocurrency and blockchain become much more common, the fundamental question for a lender remains the same: Will this borrower repay the mortgage? That means lenders would still need to assess income, debts, credit history, the property and the amount being borrowed.
Your credit score would still matter. Your loan-to-value would still matter. And unless regulators change the rules, borrowers would still have to deal with the mortgage stress test and debt-service ratios. Crypto could change the tools used to verify a mortgage application without changing the basic economics of mortgage lending.
What Borrowers Should Do Today
If a meaningful part of your down payment, assets or income comes from cryptocurrency, tell your mortgage professional early in the process.
Keep records showing where the crypto came from, how long you held it, where it was sold, the Canadian-dollar value received and where those funds went afterward. The CRA also recommends maintaining accurate records of crypto purchases and sales because dispositions can create tax consequences. A last-minute transfer from a crypto exchange into a bank account may be perfectly legitimate, but it can still create more questions than funds that have a simple and well-documented history.
Cryptocurrency does not make a mortgage impossible, but documentation becomes particularly important. Income verification, credit checks, debt-service analysis and property underwriting still apply. If crypto is converted to cash for a purchase or refinance, the lender may need to trace the source and conversion before accepting those funds.
The future Canadian mortgage may still be measured in dollars and secured against a house—but more of the verification and record-keeping behind it could become digital.
About the author: Jason Wodlinger is an Ontario Mortgage Agent Level 2. Crypto tax treatment, AML rules and lender policies can change; borrowers should verify current lender and tax requirements before relying on crypto-sourced funds.