Could the space you already own help pay for your next rental property?
How do you finance a basement apartment or garden suite in Ontario? You may use mortgage refinancing, a home equity line of credit (HELOC), a second mortgage or construction financing. Some qualifying owner-occupied projects may also use CMHC’s insured secondary-suite refinance. Before choosing, check whether the rental unit can legally be built, how the lender will value the completed property and whether projected rent can count toward mortgage qualification.
Table of Contents
Compare Basement Apartment and Garden Suite Financing
| Option | When it may fit | What to check |
|---|---|---|
| Mortgage refinance | One larger planned renovation | Available equity, income, mortgage-breaking costs |
| HELOC | Contractor payments over time | Variable interest rate and principal repayment plan |
| Second mortgage | Keep an existing first mortgage | Higher costs, fees and a realistic exit plan |
| Construction or insured suite refinance | Eligible basement or detached suite project | Approval timing, permits, appraisals and progress draws |
Start with the Ontario home renovation financing options guide for a wider comparison of loans and repayment costs.
Can You Use Home Equity to Build a Rental Unit?
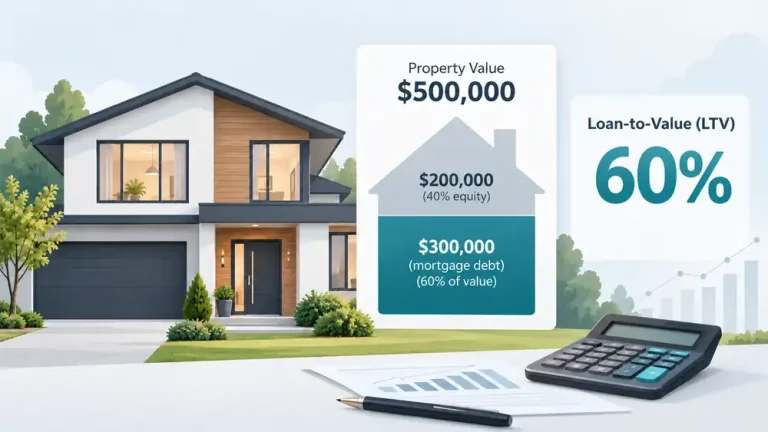
A refinance may let you replace your existing mortgage with a larger one and use some of the proceeds for construction. A home equity line of credit (HELOC) offers flexible access to approved funds, while a second mortgage can leave your first mortgage in place. Each option has different rates, fees and repayment obligations. The amount available depends on your property’s value, existing debt, income and lender rules. If you are weighing these choices, see my guide to loan-to-value ratios.
Financing a Basement Apartment
Turning a basement into a rental apartment can involve plumbing, electrical work, fire separation, ventilation, windows or exits, ceiling height and permits. A finished basement is not automatically a legal rental apartment. Ask your municipality’s planning and building departments what is permitted on your property before you agree to a construction budget or borrow money.
Ontario’s guide to adding a second unit explains building permits, zoning, inspections and safety requirements. Provincial additional residential unit rules allow more housing in many locations, but site-specific setbacks, building standards, servicing and other approvals still matter. A lender may also need contractor quotes, proof of income and an appraisal.
Budget example: A proposed $100,000 basement conversion with a 15% construction contingency needs approximately $115,000 in available project funding, before any separate financing costs. A contingency is a planning allowance, not a promise that costs will stay within budget. To understand the income test, see how lenders calculate GDS and TDS.
Can CMHC Refinance Help Fund a Secondary Suite?
There is a special insured refinancing option worth examining before assuming every renovation refinance is capped at the usual 80% loan-to-value. CMHC’s Refinance for Building Secondary Suites permits eligible owner-occupied properties with up to four total units to qualify for up to 90% loan-to-value, with a maximum as-improved lending value below $2 million and up to 30 years of amortization. CMHC’s valuation for financing is limited to the lesser of the as-improved value or the as-is value plus eligible improvement costs. These are program maximums, not guaranteed access to cash or approval.
The homeowner must already own the property, and at least one unit must be occupied rent-free by the owner or an eligible relative. The new suite must be self-contained, comply with local rules and must not be used for rentals shorter than 90 consecutive days. Additional loan funds must be used for constructing the suite, not unrelated equity withdrawals. CMHC requires approval before work starts or at an early stage.
Plan to provide building plans, cost estimates, a building permit and completion or occupancy evidence. The program also applies credit, income and debt-service requirements, mortgage-insurance premiums and progress-draw procedures. Ask the lender how much money must be advanced upfront to pay deposits and when later construction draws would become available.
How Do You Finance a Garden Suite?
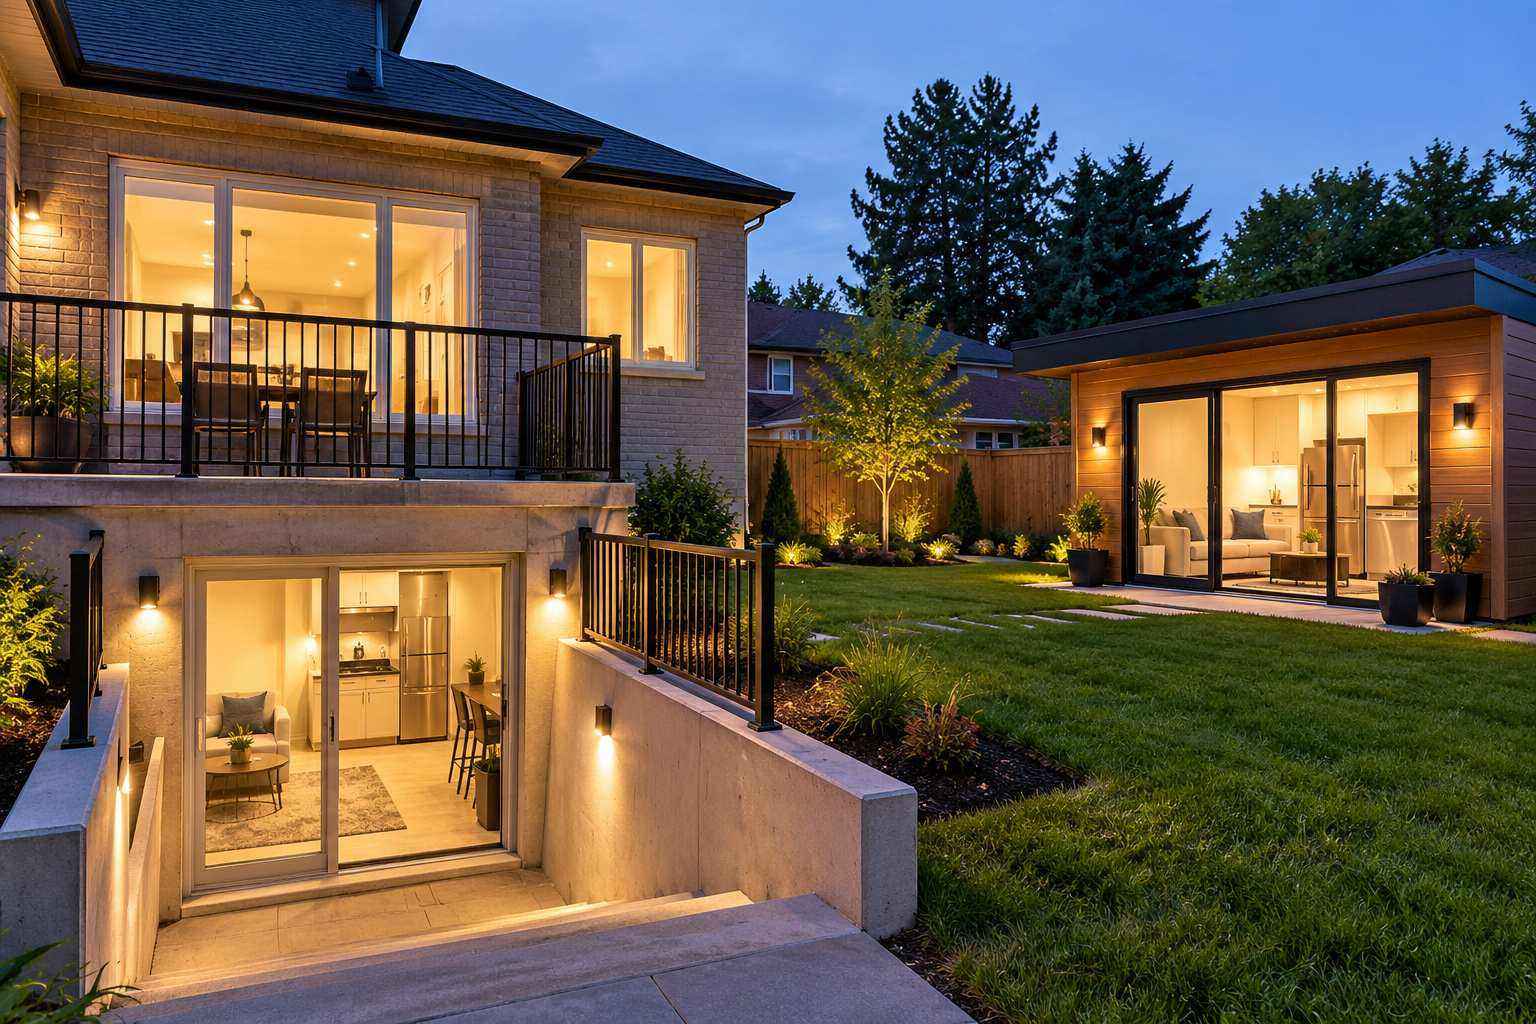
A garden suite can cost more than a basement conversion because it may need a separate foundation, sewer and water servicing, electrical connections, site work and independent access. Although Ontario allows additional residential units on many eligible properties, not every lot is suitable for a detached garden suite. Municipal requirements can still affect height, setbacks, emergency access and servicing. Ontario’s laneway and garden-suite planning guide explains why these checks matter.
Some lenders consider the expected as-completed property value; others focus on current equity and documented construction costs. If your lender issues funds in stages following inspections, arrange the contractor’s deposit and payment schedule so construction does not stop between advances. Check the available renovation financing options before signing.
Can Future Rent Help You Qualify?
Can a lender count the future rent from your basement apartment? Possibly, but not always in full. Lenders look at the property’s legal use, evidence of actual or reasonable market rent, other household income, debts and the mortgage product. CMHC’s rental-income guidance allows different approaches: for certain owner-occupied, two-unit properties that are the subject of the insured mortgage application, an eligible calculation can use up to 100% of gross rental income. Other circumstances may call for up to 50% of gross rent or a net-rental-income approach. These are CMHC calculation methods, not a promise that every lender will count projected rent.
Example: If the planned apartment could rent for $1,800 a month, gross projected rent would be $21,600 a year. Under a hypothetical 50%-of-gross calculation, the lender might use $900 per month for qualification; under an eligible up-to-100% approach it might use more. Whether either method applies depends on the insured application, property and underwriting evidence. Your real cash flow is different: vacancies, utilities, insurance, maintenance, property tax and financing costs still need to be paid. See how mortgage debt ratios work before relying on future rent.
What If Construction Costs Run Over Budget?
Renovation budgets can change after walls are opened or servicing work begins. Build a contingency into your plan and ask your lender whether additional funds could be available before work starts. For a large short-term funding gap, private financing might be an option if you have a credible exit plan, but interest, lender fees and legal costs can be substantial. Review my guide to private lenders before considering that route.
Will the Rental Unit Increase Your Property Value?
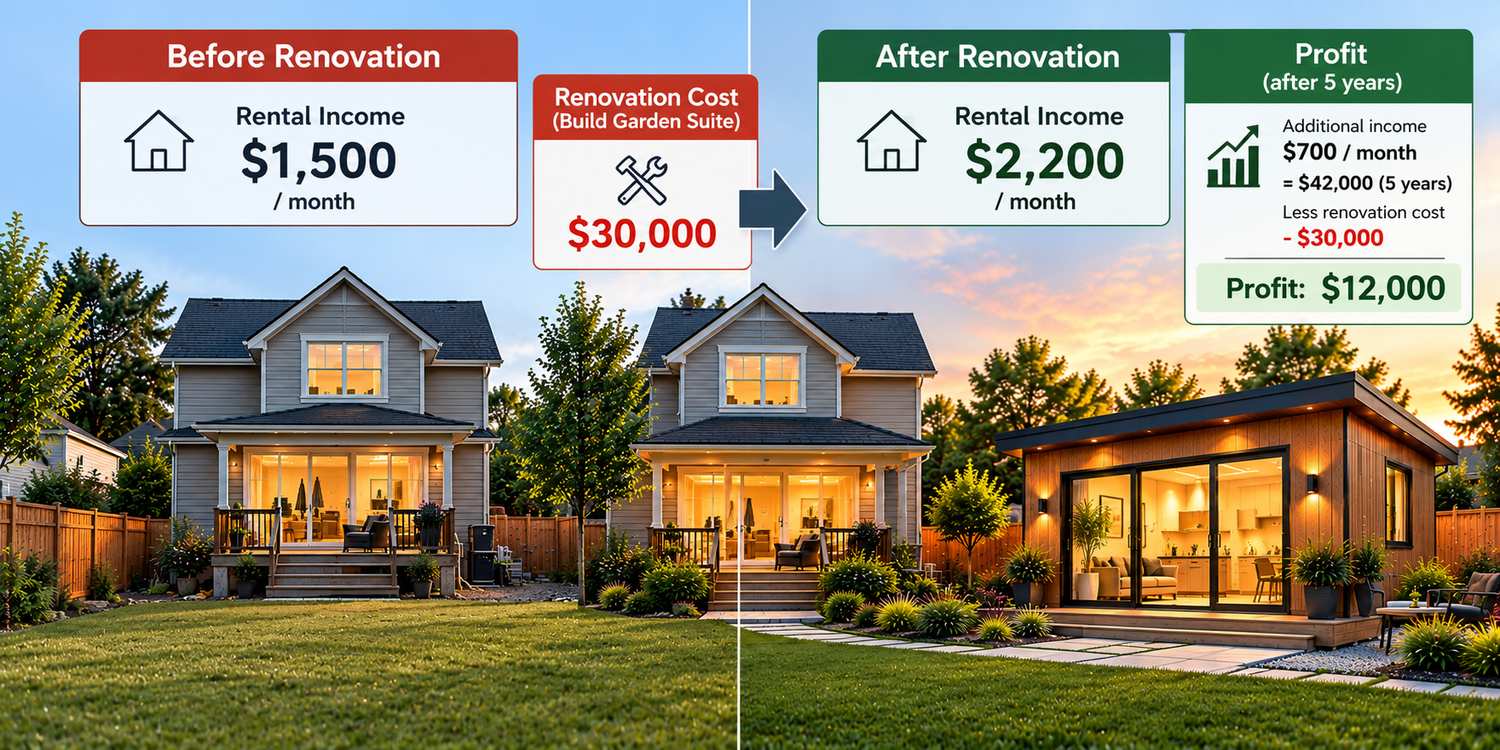
An additional legal rental unit may make a property more attractive to certain buyers, but an appraisal is not guaranteed to increase by the amount you spend. Lenders may consider comparable sales, permitted use, local demand and the completed condition. Even when a renovation increases value, refinancing still depends on equity, affordability and the lender’s policies. Compare construction costs with realistic rent, ongoing maintenance, taxes, insurance and vacancies before proceeding. Revisit how loan-to-value affects borrowing when evaluating the finished project.
Checklist Before Financing a Rental Suite
- Confirm legality: ask your municipal planning and building departments about zoning, permits, servicing and inspections.
- Obtain detailed quotes: include an allowance for unforeseen construction work and the timing of deposits.
- Get the lender’s requirements: confirm acceptable property value, qualification, funding advances and whether projected rent counts.
- Estimate cash flow: deduct realistic vacancies, maintenance, insurance, utilities, taxes and mortgage costs from projected rent.
- Review insurance: tell your insurer about construction and your intention to rent out the finished unit.
Summary
Financing a basement apartment, garden suite or rental renovation starts with understanding how much equity you can access and what mortgage payments you can afford. Refinancing, a HELOC, a second mortgage or construction financing may be suitable depending on the property, your income and the project’s scope.
Before committing to construction, confirm municipal approvals, prepare a realistic budget with a contingency, and ask how your lender will assess any projected rental income. A completed rental unit may add value, but neither the rent nor an increase in appraised value is guaranteed. Reviewing the financing plan before signing a construction contract can help you avoid costly surprises.