For some homeowners, yes. But could it also change what a lender lets you borrow?
Table of Contents
What Is Changing?
Ontario has formally reduced the Ontario Electricity Rebate (OER) from 23.5% to 15.7%, effective November 1, 2026. The change is set out in Ontario Regulation 328/26, filed October 9.
That is a decrease of 7.8 percentage points, or roughly one-third of the previous rebate. It does not mean the entire electricity bill is going up by one-third. Most eligible residential customers receive the OER automatically as a separate bill credit, according to Ontario’s energy-cost guidance. When deciding whether to stay, renovate or move, this is one more expense to include when comparing the cost of housing choices.
How Much More Could You Pay?
For illustration, assume the charges eligible for the rebate stay the same:
- Eligible electricity charges: $150
- Previous rebate (23.5%): $35.25
- New rebate (15.7%): $23.55
- Reduction in rebate support: $11.70 per billing period
Higher utility expenses can strain your household budget, but they do not change how banks analyze your income when reviewing a mortgage application.
Your actual bill may also be affected by changes in electricity use, rate-plan prices, delivery charges and taxes. The Ontario Energy Board explains rate plans including Time-of-Use, Tiered and Ultra-Low Overnight. It reviews electricity rates for November 1, so the exact future bill cannot be inferred from the rebate change alone. Higher running costs can also change the payback period when assessing home renovations and their financing.
Could Rental Properties Cost More?
For landlords who pay the hydro bill, a smaller rebate can reduce the margin between rent collected and expenses paid. Even buyers encouraged by lower Ontario new-home prices need to account for the ongoing cost of operating a rental property. This matters when electricity is included in rent, common areas are on the owner’s meter, or multiple units share an account. If a tenant pays their own eligible bill, that tenant usually faces the direct change instead.
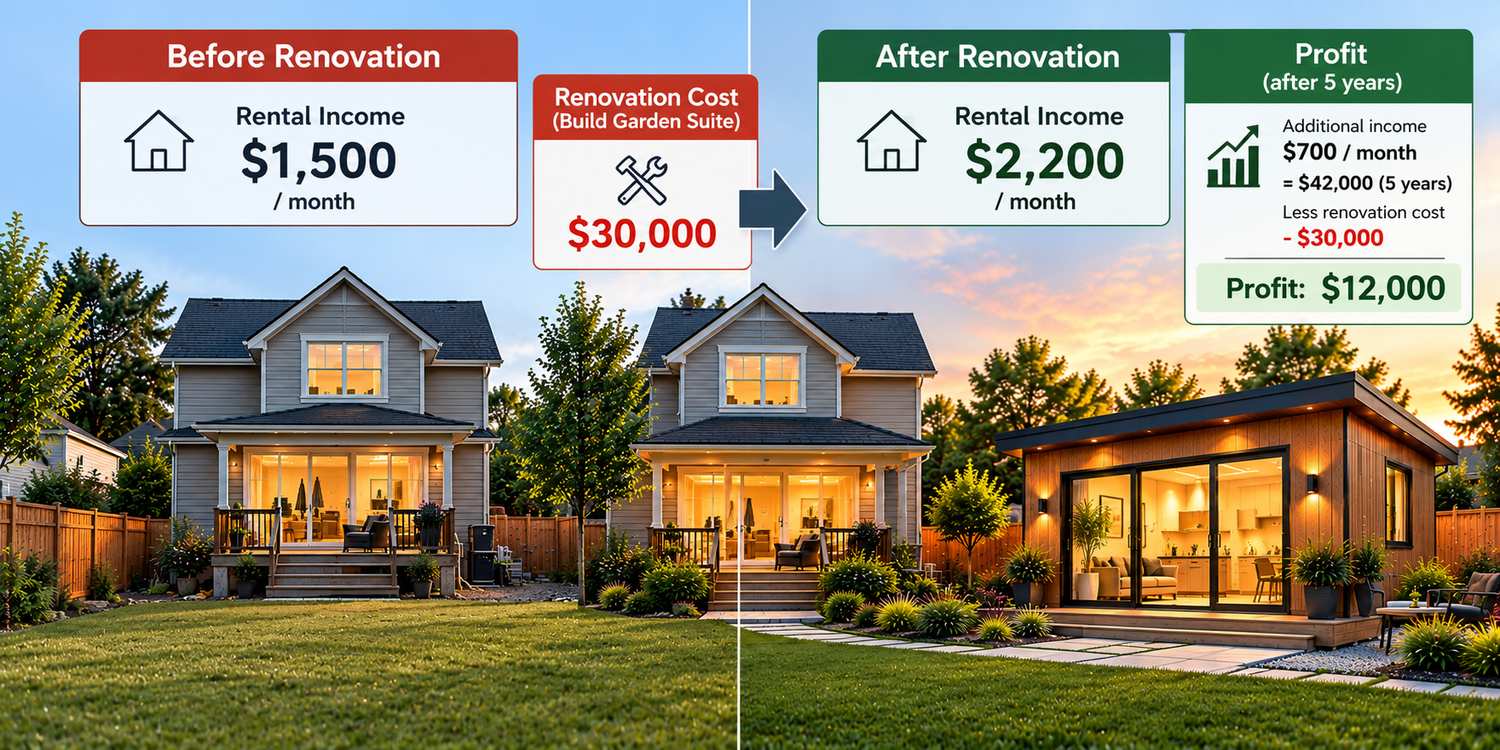
The rebate change alone does not predict any particular landlord’s electricity bill. Rental financing assessments should use realistic rental-income and expense assumptions, not gross rent alone.
Will It Affect Your Mortgage Qualification?
Not automatically. Standard Gross Debt Service (GDS) calculations use mortgage payments, property taxes, heating costs and the applicable portion of condo fees. They do not simply add every dollar of a household electricity bill to the formula. The distinction is confirmed by Ontario mortgage-regulator guidance and CMHC’s debt-service methodology.
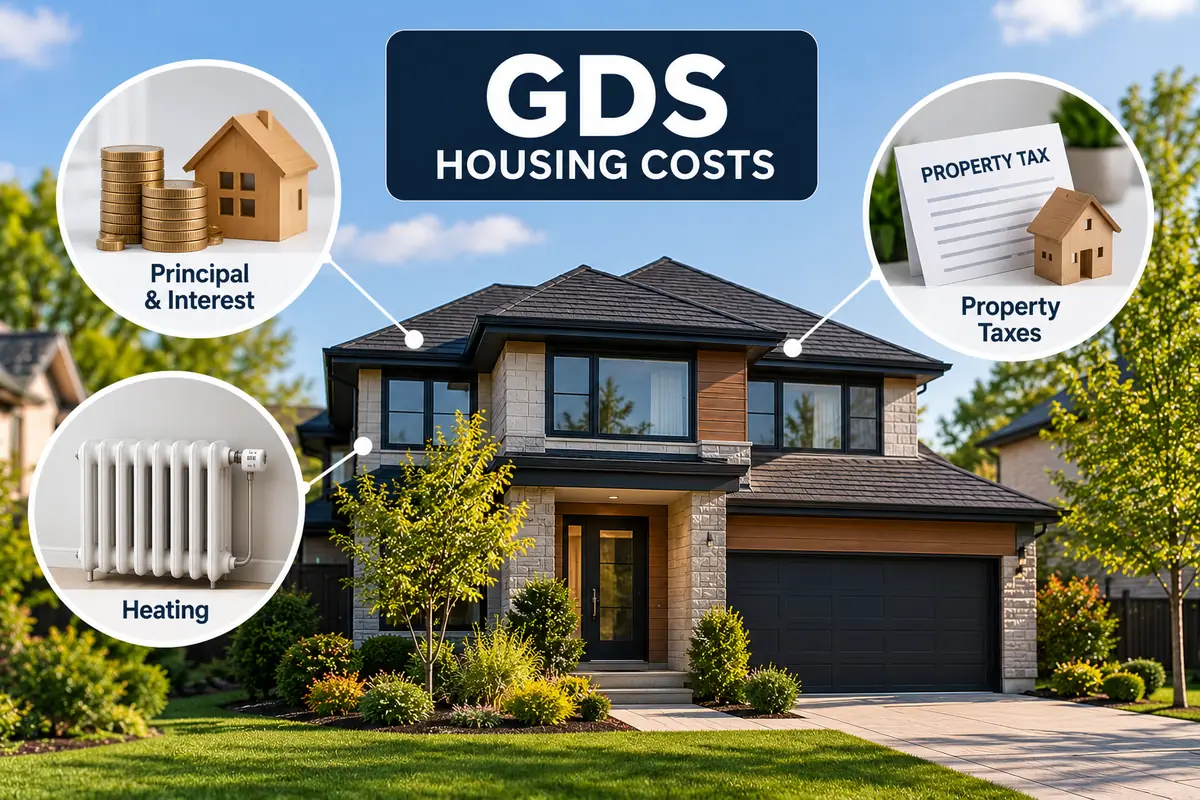
But there is an important exception. If the home is heated with electricity, electricity-based heating costs matter to the lender’s heating allowance. The treatment depends on the property and underwriting approach. Our article on GDS, TDS and mortgage stress tests explains why everyday affordability and the lender’s mathematical qualification are not identical.
What Should Ontario Homeowners Do?
Compare the OER line on your next bill with the previous bill; check your eligible charges before estimating the increase. Review whether your current electricity price plan matches your usage. If you own a rental property, check who actually pays for electricity and how the revised amount affects your cash flow.
Separate assistance and energy-efficiency programs may be available to eligible households; their requirements are different from the OER. Ontario lists other energy credits and programs. If you are evaluating insulation, a heat pump or other energy work, compare potential savings with the project’s cost and the mortgage financing options for upgrades before committing to the expense.
If you are financing an electrically heated home or a rental property where you pay the utilities, use the actual costs in your budget and ask how the lender treats the heating expense.