A seemingly cheaper mortgage rate can become the more expensive choice if you need to sell, switch lenders or refinance before your term ends.
What Is Ottawa Proposing?
In the November 5 federal budget, Ottawa announced plans to consult on clearer prepayment-penalty information for insured mortgages. It also proposed regulations for improved public reporting of insured mortgage rates by the Bank of Canada. Neither announcement sets a lower penalty that lenders must charge. Read the federal budget language.
Mortgage Professionals Canada highlighted both measures in its November 6 summary. The consultation is specifically about mortgages covered by mortgage default insurance; it should not be mistaken for an announced reform of every Ontario mortgage. The budget does not give a firm consultation date, final formula or implementation date. Read the industry’s budget analysis. For other housing measures in the same budget, see our November 5 budget overview.
When Can a Penalty Apply?
A closed mortgage typically limits how much extra principal you may repay without a charge. Selling your home, refinancing to borrow more, or moving your mortgage to another lender before the term expires can trigger a prepayment penalty. An open mortgage generally permits early repayment without that penalty, although other fees may apply.
A renewal at term-end is different from breaking a contract early. If a move is possible, ask whether your mortgage is portable, meaning it may be transferred to another eligible property subject to lender approval. Your lender may also allow annual lump-sum payments that reduce the balance before a penalty is calculated. Review Canada’s mortgage penalty guidance. If selling is one option, our renovate, sell or downsize comparison explains how moving costs and mortgage portability fit together.
Why Do Lenders Calculate Different Amounts?
For many closed fixed-rate mortgages, the charge is generally the higher of three months’ interest or an interest rate differential (IRD). An IRD estimates the interest difference associated with ending the term early; the precise formula depends on the contract. Closed variable-rate mortgages often use three months’ interest, but you must check your lender’s terms.
Two lenders offering similar rates can still produce very different penalties. Some calculations use posted rates and the original discount, while others use different comparison rates or methods. Federally regulated lenders already have disclosure obligations, so the new budget discussion concerns possible improvements rather than the first introduction of penalty disclosure. Our comparison of refinancing expenses also discusses the separate administrative costs borrowers may encounter.
What Might Breaking a Mortgage Cost?
In another example, consider these illustrative assumptions (Assumption): a $400,000 balance, a 4.8% annual mortgage rate and 24 months left in the term. Three months’ simple interest would be about $4,800. A simplified IRD using a one-percentage-point rate difference over two years would be about $8,000.
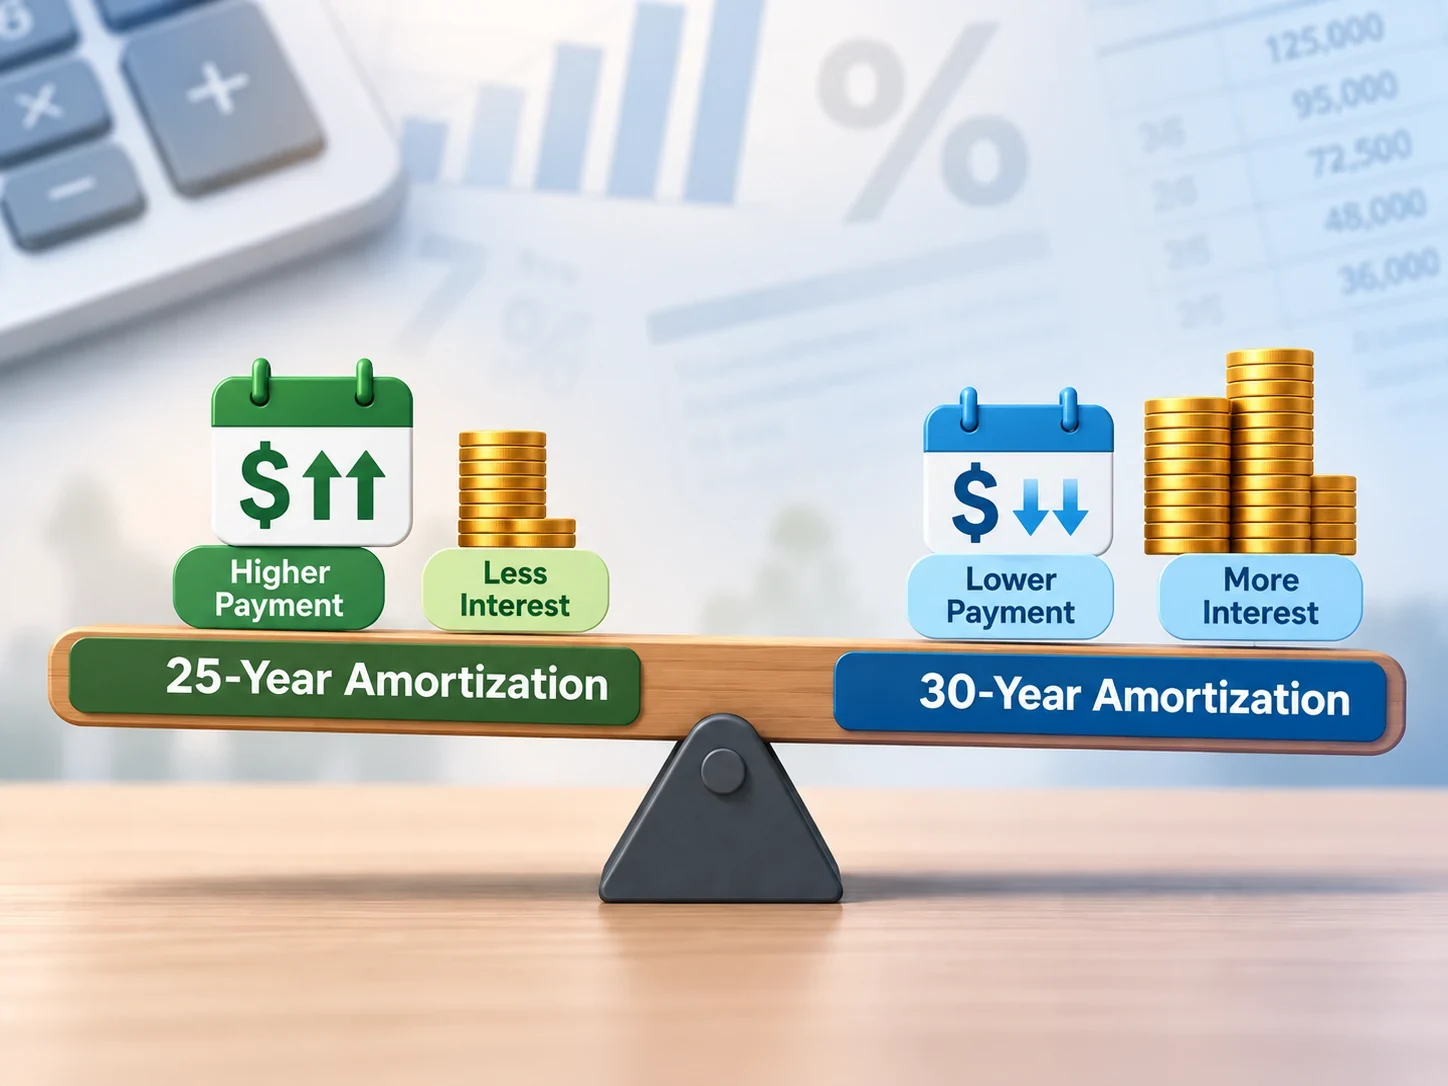
Those figures are not lender quotes. Actual IRD formulas can use posted rates, discounts, remaining payments and other contract-specific inputs, so the result may be materially different. Ask your lender for a dated written payout statement before relying on an estimate. Our 25-year versus 30-year amortization comparison explains why the balance remaining at that point may differ.
Could a Lower Rate Still Cost More?
In another example, assume a constant $400,000 balance and a new interest rate just 0.25 percentage points lower (Assumption). The rough annual interest saving is $1,000 before considering principal repayment, fees or the term structure. An $8,000 break penalty would outweigh two years of that simplified saving.
A lower payment also does not guarantee refinance approval. The new lender may assess income, credit, property value and debt ratios, and there may be legal, discharge or appraisal costs. Our guide to mortgage refinancing in Ontario explains why approval and household affordability are different questions.
What Should Ontario Borrowers Compare?
Ask each prospective lender for both penalty scenarios: three months’ interest and an illustrative IRD at an assumed early-exit date. Compare prepayment privileges, portability, restrictions on refinancing, discharge fees and how the lender determines its comparison rate. Request the calculation in writing and ask how it would change if rates fell.
Before changing lenders, compare the total transaction cost with the interest and payment savings over the period you expect to keep the mortgage. At renewal, compare new offers without assuming that the lowest advertised rate is the best overall fit. If a new approval is required, our mortgage stress test guide explains another obstacle beyond the quoted rate. Our article on Canada’s broader budget housing changes explains the separate proposals for buyers.
Will Penalties Actually Be Reduced?
As of November 7, 2026, the budget proposes transparency, not a penalty cap, prohibition or immediate reduction. Clearer disclosure could make lender offers easier to compare, but whether charges themselves change remains unknown. Our review of other proposed mortgage-rule changes makes the same distinction between proposals and available financing. For an upcoming sale or refinance, your current mortgage contract and lender’s actual payout figure still matter most.