President Trump has repeatedly referred to Canada as the “51st state.”
Some clients have asked me about it from a mortgage perspective. I prefer to leave politics out of financial advice; it keeps things clearer.
But allow me one small detour: I’m a proud Canadian, and I love our sovereign, independent country.
I enjoy looking at the world through different lenses, and one of my favourites is that of real estate financing. So those headlines got me wondering:
How do Canadian mortgage rules compare with those in the United States?
Table of Contents
Could Your Mortgage Rate Stay Fixed for 30 Years?
In the United States, borrowers can commonly obtain a 30-year fixed-rate mortgage. The interest rate stays fixed for the full 30 years, provided the original loan remains in place. That means no mandatory rate renegotiation every five years. Freddie Mac explains how fixed-rate loans work.
Canada usually works differently. Most Canadian mortgage holders have terms of five years or less, even when payments are calculated over 25 or 30 years. At the end of the term, borrowers generally renew at the rates then available. A 25-year versus 30-year amortization is about the repayment schedule, not a 25- or 30-year rate guarantee.
U.S. rule sources: Freddie Mac — Fixed-rate mortgages.
Would You Pass the Same Mortgage Stress Test?
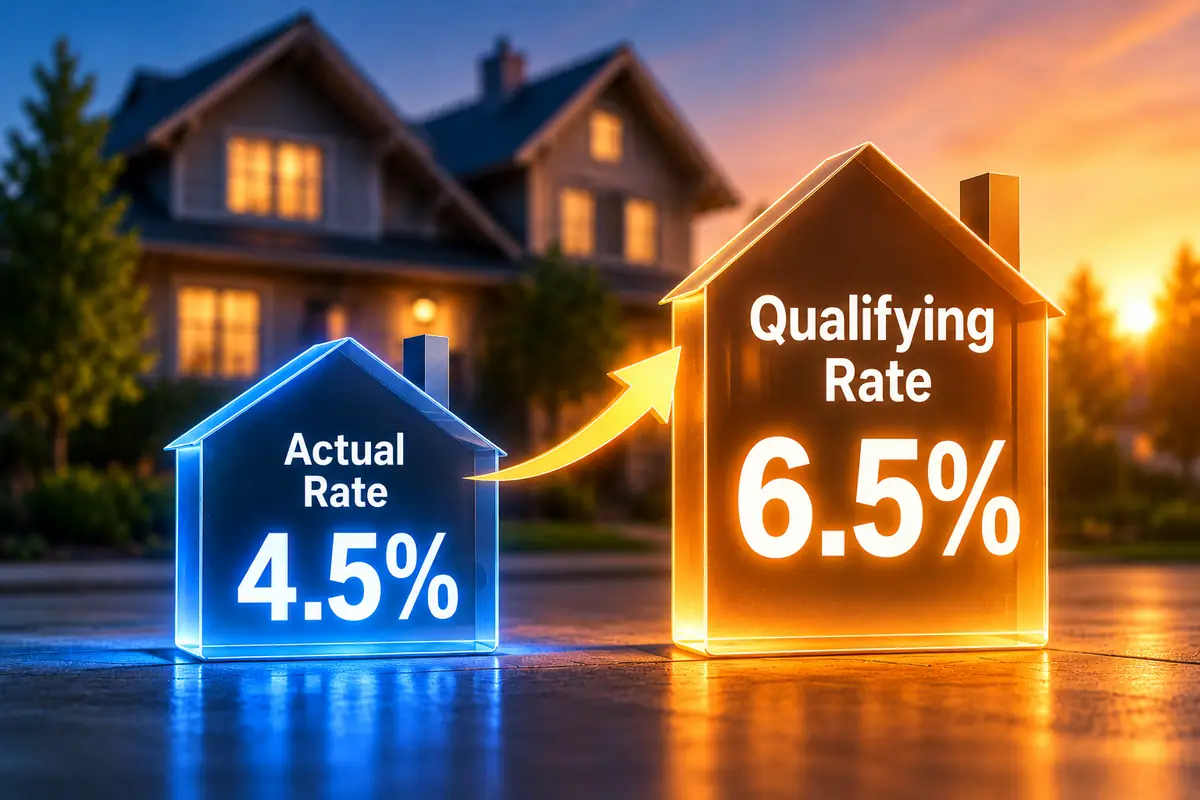
In Canada, federally regulated lenders generally test whether borrowers could manage payments at the higher of 5.25% or the contract rate plus two percentage points. For example, a 4.5% rate generally means qualifying at 6.5%. That calculation can reduce the mortgage you qualify for even if the actual payment seems manageable. Canada’s banking regulator describes the test.
American lenders must generally assess income, assets, employment, credit history and expenses to determine whether a borrower can repay a mortgage—similar to how Canadian banks analyze mortgage income. They must also account for potentially higher payments on certain loans with changing interest rates. Rather than applying Canada’s standard two-percentage-point buffer, U.S. lenders follow ability-to-repay requirements and the rules for the loan involved.
U.S. rule sources: CFPB — Ability-to-repay rule; CFPB — Regulation Z, § 1026.43.
Could You Buy With Less Money Down?
For an eligible insured Canadian home purchase, the minimum down payment is 5% of the first $500,000 and 10% of the portion above $500,000 for prices below $1.5 million. At $1.5 million or more, the general minimum is 20%. Canada’s down-payment guidance explains these thresholds.
In the United States, eligible buyers may qualify for an FHA-insured mortgage with as little as 3.5% down. Some qualifying veterans can obtain VA-backed mortgages with no down payment. These are specific programs, not offers available to every buyer. The U.S. government explains FHA loans.
U.S. rule sources: HUD — FHA loans; VA — Purchase-loan eligibility and benefits.
Can Americans Deduct Their Mortgage Interest?
Sometimes. In the U.S., interest on a qualifying home mortgage may be deductible on a federal tax return if the homeowner itemizes deductions and meets applicable debt limits and other conditions. That is not an automatic tax break for every homeowner. Financing an income-producing property is a separate consideration; my Canadian guide to financing basement apartments and garden suites covers a related borrowing situation. The Internal Revenue Service explains the U.S. deduction restrictions.
In Canada, interest on borrowing used to purchase and personally occupy a principal residence is generally not deductible. Interest on money borrowed for qualifying income-earning purposes can be treated differently. Canada Revenue Agency explains the personal-use distinction.
U.S. rule sources: IRS — Topic 505, mortgage-interest deductions.
What If You Pay Off Your Mortgage Early?
In Canada, a 25- or 30-year mortgage amortization is different from the mortgage term. Paying off a closed mortgage before that term ends—perhaps to sell or refinance—often triggers a penalty. Depending on the mortgage, it may be based on three months’ interest or an interest-rate-differential calculation. Open mortgages generally offer more flexibility. The Financial Consumer Agency of Canada explains these charges.
In the United States, prepayment penalties are not universal: whether one applies depends on the mortgage terms. Federal rules also restrict when these penalties are allowed on covered loans. That can make selling or refinancing more flexible for someone with a penalty-free loan. The U.S. consumer regulator explains what to check. In Canada, refinancing an existing mortgage often means weighing a potential penalty against the savings.
U.S. rule sources: CFPB — Early-repayment penalties; CFPB — Regulation Z, § 1026.43.
The Bottom Line
There is no single winner in this comparison. American borrowers may have access to much longer fixed-rate commitments and certain lower-down-payment programs. Canadian borrowers operate within different renewal, qualification and mortgage-insurance rules. In either country, the details of the particular mortgage determine what someone can afford, how flexible the loan is and what it could ultimately cost.
U.S. rule sources: Freddie Mac — Fixed-rate mortgages; HUD — FHA loans; VA — Purchase-loan eligibility and benefits.