An AI data centre could be built miles from your home, yet its infrastructure costs might eventually land on your property-tax bill—and shrink the mortgage you qualify for.
That question is worth asking in Oakville, where the town is reviewing how data centres might affect local services. However, one distinction is essential: there is no verified evidence that an Oakville AI data centre has increased residential property taxes. The mortgage impact explored here is a potential consequence, not an established result.
Why Is Oakville Reviewing AI Data Centres?
On October 16, 2026, Oakville confirmed its temporary restrictions on certain new data-centre developments remained in place after the appeal period ended without an appeal. Council passed the one-year interim by-law in August while staff examine electricity and water demand, infrastructure capacity, noise and land-use compatibility. In its October 16 municipal announcement, the town said it had not received a formal data-centre development application.
The bigger concern is who ultimately pays for growth. During October’s local candidate interviews, infrastructure demands and responsibility for costs were raised as issues. Those concerns do not establish that residents have actually been billed for a proposed facility.
Who Would Pay for New Infrastructure?
A major data centre could require investments in water and wastewater systems, roads or electrical connections. But the cost of a new connection and the cost of broader municipal services may fall under different funding arrangements. A large infrastructure bill does not automatically become a residential property-tax increase.
Both Oakville and Halton Region collect development charges intended to recover eligible growth-related infrastructure costs. Halton’s published development-charge rules include roads, water and wastewater, and Oakville’s municipal development-charge program covers other eligible services. Before reaching a conclusion about any particular data centre, we would need its applicable charges, exemptions, direct contributions and a breakdown of costs not otherwise recovered.
Could Existing Electricity Customers Pay More?
Ontario is already examining this risk. In August 2026, the province proposed a separate electricity rate class for large new data centres, intended to keep their growth costs from increasing existing customers’ bills. The published provincial regulatory proposal describes that approach; it is not confirmation that every proposed measure is in force.
Water bills are a separate question. Halton sets residential water and wastewater rates, and an increase in those rates would not necessarily be an increase in municipal property taxes. No data-centre-related rise in Oakville homeowners’ water charges has been established.
Could a Data Centre Eventually Increase Property Taxes?
It’s possible, but it would depend on how the project is funded. For example, a future project creates public infrastructure costs that are not fully covered by developers, utility funding or other revenues. If a municipality later chose to pay for part of those remaining costs through its property-tax levy, homeowners could face higher taxes.
However, the opposite outcome is also possible. A taxable commercial or industrial development could add municipal property-tax revenue that helps offset some public costs. Without an actual project, a financial impact assessment and municipal budget decisions, nobody can reliably say whether homeowners’ taxes would increase, decrease or remain unchanged because of a data centre.
How Would Higher Property Taxes Affect Your Mortgage?
This is where the mortgage connection becomes concrete. When a Canadian lender calculates your gross debt service ratio, it normally includes property taxes along with mortgage payments and heating costs. Federal mortgage qualification guidance uses 39% for gross debt service and 44% for total debt service as general reference limits, with lender-specific rules and exceptions possible.
Suppose annual property taxes increased by $600. That would add $50 a month to the housing costs used in a qualification calculation. If you were already at your lender’s limit, that extra $50 might reduce the mortgage payment—and therefore mortgage amount—the lender would approve.
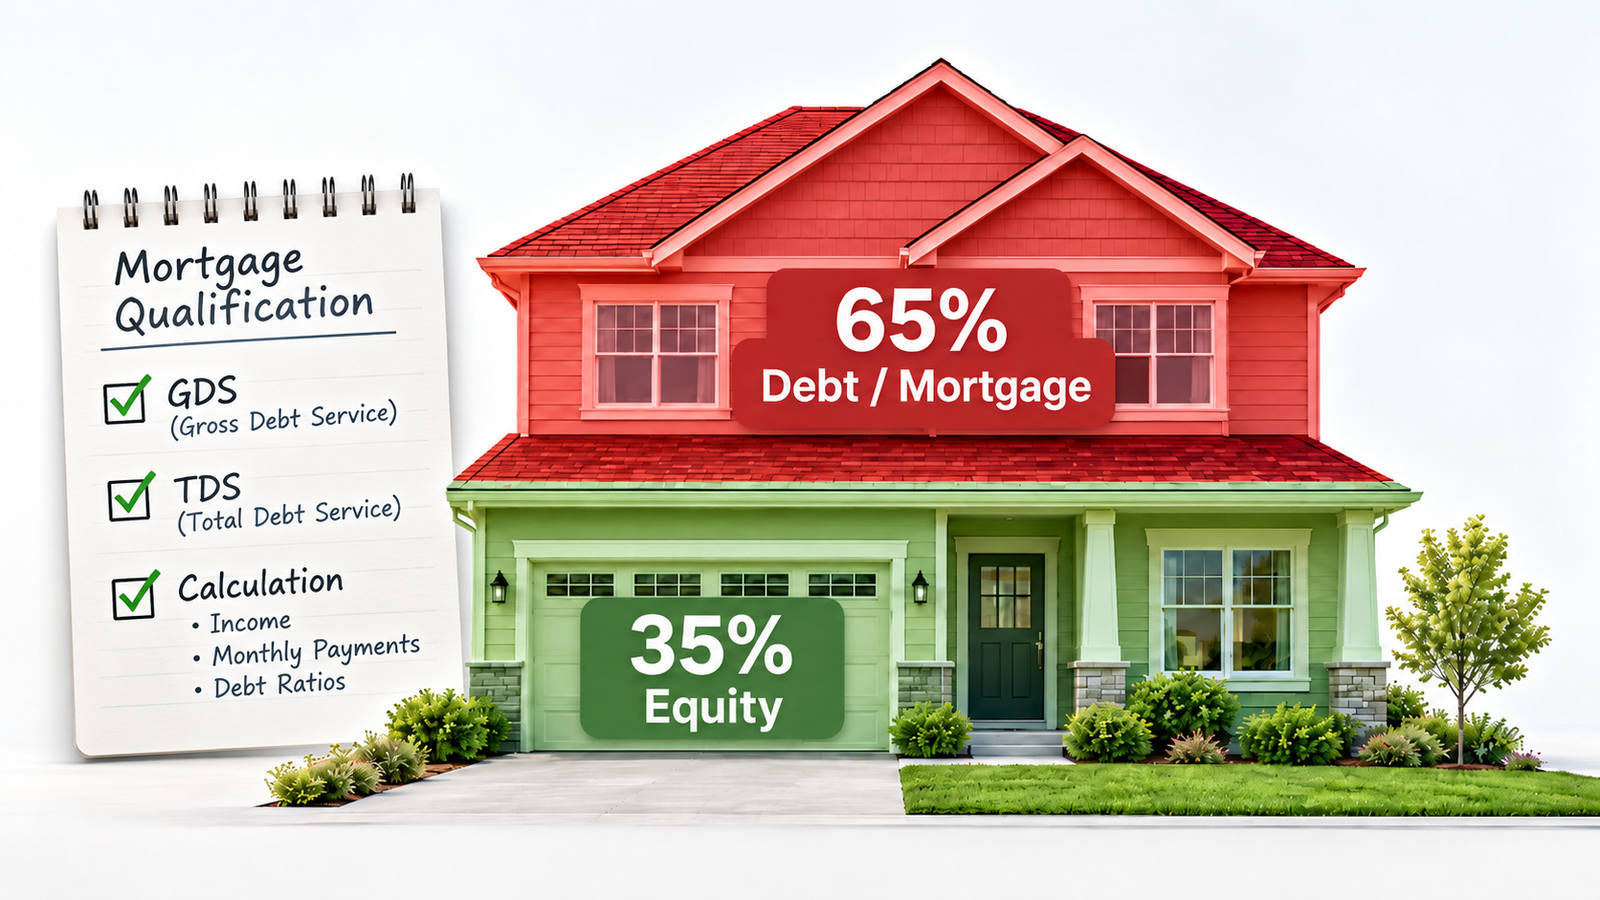
The $600 example is illustrative only; it is not an Oakville data-centre tax forecast. And approval isn’t the same as affordability: even if your existing mortgage payment stays the same, higher annual property taxes could squeeze your household budget. You can read more about how GDS and TDS work.
So What Should Ontario Homeowners Watch?
Look for real applications, infrastructure cost estimates, development-charge calculations, utility agreements and future municipal budgets. Those documents could show who pays and whether any portion reaches residential taxpayers. Until then, saying an AI data centre will increase your property taxes or reduce your mortgage approval would go beyond the evidence.
New technology can bring economic benefits as well as infrastructure demands. If you are weighing the cost of owning a home, our article on Ontario electricity costs and homeownership explores another part of that calculation.