CMHC found that 11.1% of Greater Toronto and Hamilton Area mortgage investment entity balances were 90 days or more overdue in early 2026.
What Does 11.1% Actually Measure?
Before looking at the number, three terms matter. GTHA stands for the Greater Toronto and Hamilton Area. Mortgage investment entities (MIEs) are non-bank lenders, including mortgage investment corporations and certain other private lenders, that often offer short-term mortgages to borrowers who may not qualify at a bank. Mortgage balances means the total dollars still owed on those mortgages, not the number of borrowers or homes.
CMHC’s Fall 2026 mortgage industry report found that 11.1% of GTHA mortgage investment entity (MIE) balances were at least 90 days overdue in Q1 2026, versus 3.0% in Q3 2023. This is a share of mortgage balances, not the percentage of homeowners missing payments. The MIE category does not cover every private mortgage.
Nationally, MIEs accounted for only 1.8% of outstanding mortgage balances in Q1 2026. Ontario’s broader mortgage arrears rate was 0.32% in Q2 2026, a different population and period. Neither statistic counts homes that will ultimately be sold under power of sale.
Why Are Private Mortgage Arrears Rising?
Private lenders can finance borrowers whose income, credit history or circumstances do not fit a conventional bank’s requirements. Their higher borrowing costs can make financing expensive. For a closer look at your options, see our related articles on:
- How to stop a power of sale
- Steps to take before a power of sale occurs
- How to deal with private lenders
- What private mortgages cost
- Alternatives worth exploring before private financing
CMHC reports that 69.7% of GTHA MIE mortgages were interest-only in Q1 2026, leaving principal largely unpaid. Among uninsured MIE mortgages, 9.2% had loan-to-value ratios above 80%; meanwhile, 29.0% of GTHA MIE mortgages had borrowers with total debt-service ratios above 60%. These measures may overlap and must not be added together.
Why Renewing Your Mortgage May Not Help
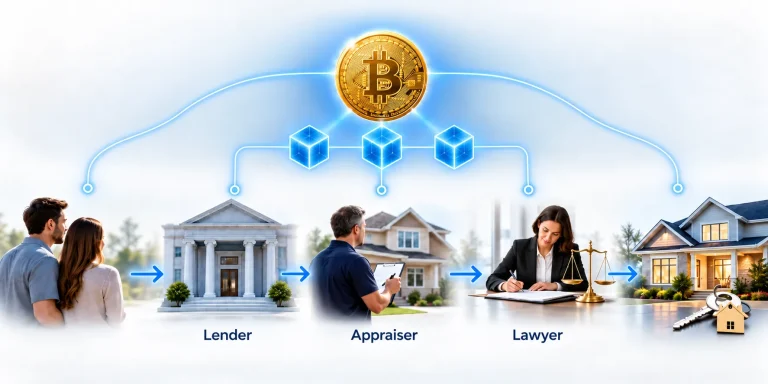
Imagine a borrower who took a one-year private mortgage intending to move to a bank later. An interest-only payment may have kept monthly costs manageable, but the principal remains due at maturity. A weaker property appraisal, unstable income or damaged credit could then prevent the expected refinance.
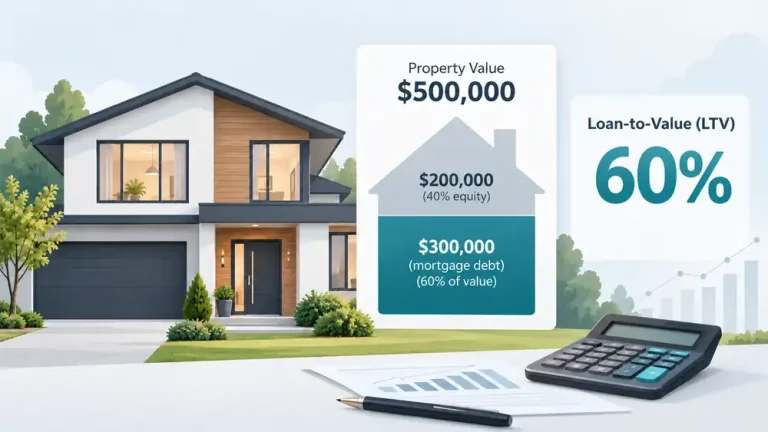
Today’s lending decision uses today’s accepted property value, not what the owner paid in the past. The mortgage loan-to-value calculation explained shows why declining equity can shrink refinancing choices. Affording the current payment does not guarantee approval for a replacement loan.
For more information about what to do before mortgage default or during a power-of-sale situation, see our article on how to stop power of sale.
Are More Forced Sales Coming?
Not necessarily. Some overdue MIE loans can be resolved through repayment, renewals, refinancing or voluntary sales, while others may proceed to enforcement. CMHC identifies stress in a narrow, higher-risk segment, but its 11.1% statistic is not a forced-sale forecast.
CMHC’s October mortgage arrears news release anticipates rising broader Ontario arrears into mid-2027 without describing a nationwide mortgage crisis. For someone carrying a private mortgage today, the decisive question is whether an affordable, credible exit exists before maturity.