Ontario has frozen OSAP payments to some education institutions—but could that stop you from being approved for a mortgage?
For some Ontario students, the answer could be yes—even when their mortgage application has nothing directly to do with their college.
The OSAP payment freeze is a timely reminder that mortgage approval depends on more than your career ambitions. Lenders need to understand the money coming in, the debts going out and whether your income is likely to continue.
Why has Ontario frozen OSAP funding?
Imagine leaving a steady job to retrain for a new career, only to discover that the student funding you expected is on hold. Suddenly, tuition, household bills and even your plans to buy a home may be in jeopardy.
On October 6, 2026, Ontario announced a pause on OSAP payments associated with private postsecondary institutions while an audit investigates serious concerns about the integrity of applications. The province has discussed possible low-interest third-party loans, but details have not yet been finalized. This is not a freeze on every Ontario college or university. Because the province is examining application integrity, the distinction between legitimate financial aid and misrepresentation matters; similar documentation issues are explored in the context of mortgage fraud. See the Ontario government’s announcement.
Can OSAP grants count as mortgage income?
Usually, a student loan is borrowed money, not employment income. A grant or bursary may not have to be repaid, but that does not automatically make it acceptable mortgage-qualifying income.
Mortgage lenders generally look for income that is verifiable, sufficiently stable and likely to continue. Some may consider certain ongoing stipends or other non-employment income under specific policies, but acceptance of OSAP grants must be confirmed with the individual lender. The treatment of grants is one example of how banks analyze different sources of mortgage income.
What if your OSAP funding is suddenly frozen?
If your OSAP funding stops, you may need to find another way to cover tuition and living expenses, take on additional debt or reconsider your education plans. Although OSAP funding is not automatically mortgage-qualifying income, these changes could affect your financial situation and mortgage affordability.
If you already have a mortgage approval but have not closed your purchase, tell your mortgage agent promptly if any income you were relying on stops, your debts increase or your financial circumstances change materially. Approval conditions may need to be reassessed. Avoid taking on a new personal loan or line of credit without checking the effect on your mortgage first.
If you already own a home and your income has fallen, the options may resemble those facing homeowners after a job loss, including the need to address payment difficulties early.
Will a break from work to attend school hurt your application?
Taking time off to study is not automatically disqualifying. A lender may want to know why you stopped working, what qualifications you earned, when you returned and whether your new income is reliable.
Someone returning to the same field with a guaranteed salary may present a different risk from someone starting a commission-based career. The connection between employment uncertainty and Canadian mortgages is especially relevant when a borrower is retraining for a new occupation. A signed employment agreement, recent pay stubs and evidence of prior experience can help, but lender rules on probation and income history vary.
Can doctors or dentists qualify before graduating?
Some specialized mortgage programs recognize the earning potential of medical professionals. For example, certain physician programs may consider projected income for eligible medical residents or newly practising doctors, subject to strict requirements. That does not mean every medical student can qualify on a future doctor’s salary. Even for high-earning professions, the relationship between salary and the home price you can afford still depends on which income a lender actually accepts.
Dentists and other professionals may have access to specialized lender programs, but the eligible occupation, licensing stage and income treatment must be checked lender by lender. It is best to not assume that lawyers, pharmacists, veterinarians or accountants automatically qualify for projected-income financing.
How does OSAP debt affect mortgage approval?
Student loans can reduce the mortgage amount you qualify for because lenders include applicable debt obligations when calculating your total debt service ratio (TDS). A repayment-free period does not necessarily mean the debt is ignored.
The effect is captured in mortgage stress-test calculations and the GDS and TDS ratios. The Financial Consumer Agency of Canada also lists student loans among debts considered in mortgage affordability. The payment a lender uses can differ from your current statement, so request an actual qualification calculation before paying off a loan solely to improve approval odds.
Can parents help a student buy a home?
A parent may be able to help as a co-borrower, guarantor or provider of a permitted down-payment gift. Those arrangements have different legal and financial consequences, and a parent who signs the mortgage may become responsible for the debt.
A gifted down payment can help with the cash needed to purchase, but it does not replace the requirement to qualify for mortgage payments. When the total down payment is less than 20%, high-ratio mortgage requirements may also affect the purchase.
Should you refinance your home to pay for school?
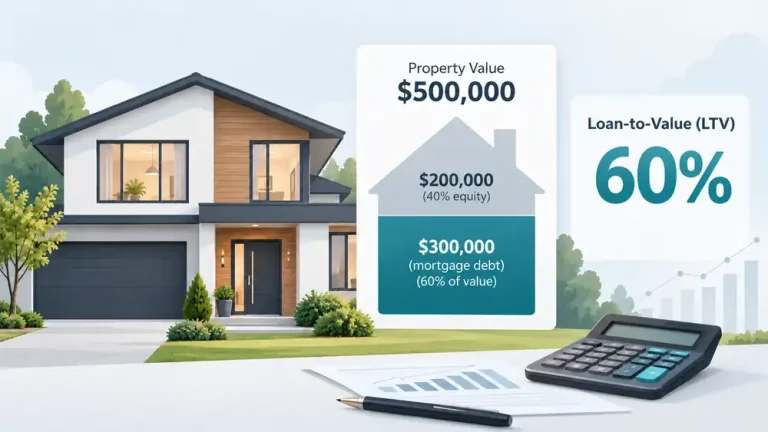
Homeowners may consider a refinance or home equity line of credit to fund education when student assistance is delayed. But using your home as security adds risk: if repayment becomes difficult, your property is exposed.
Compare the full borrowing cost, repayment schedule and available equity before proceeding. The costs and trade-offs are the same ones homeowners should assess when refinancing an existing mortgage.
What should you do before applying?
Gather proof of current income, your employment and education timeline, student loan balances, expected repayment amounts and any funding notices. If you are changing careers, ask whether a signed job offer, probationary employment or professional training status will satisfy the proposed lender.
Also review how your credit score affects mortgage qualification and avoid assuming that future earnings will count before they exist. A mortgage agent can compare policies before you commit to a purchase or new education-related debt.
Mortgage qualification depends on the lender, mortgage insurer where applicable, borrower documentation and current underwriting rules. This article is general information, not a promise of financing.