Canada’s advertised rents have fallen for two years. That’s good news for many renters, but could it make it harder to qualify for a mortgage on an investment property?
Table of Contents
Canadian rents have fallen for two years
The October 2026 National Rent Report from Rentals.ca and Urbanation reports an average Canadian asking rent of $2,034 in September, down 4.2% year over year. It marks 24 consecutive months of annual declines, with asking rents 7.3% below two years earlier. Ontario asking rents were down 4.8% year over year.
These figures describe advertised asking rents, not necessarily the rent paid by existing tenants. That distinction is essential when assessing a rental property’s financing, since a lender’s analysis of qualifying income depends on documented and eligible earnings rather than national averages.
Can falling rents affect mortgage approval?
A lender may count eligible rental income when determining how much you can borrow, but the calculation depends on the property and program. Under CMHC rental-income guidance, an owner-occupied two-unit property that is the subject of the application can use up to 100% of gross rental income. For an owner-occupied three- or four-unit property, or a two- to four-unit non-owner-occupied property that is the subject of the application, CMHC permits either up to 50% of gross rent or a net-rental-income approach. Individual lenders may apply their own equivalent or more conservative underwriting rules.
The lender may request leases, evidence of deposits or an appraiser’s market-rent opinion. Lower expected rental income can affect debt-service calculations, especially for a vacant unit.
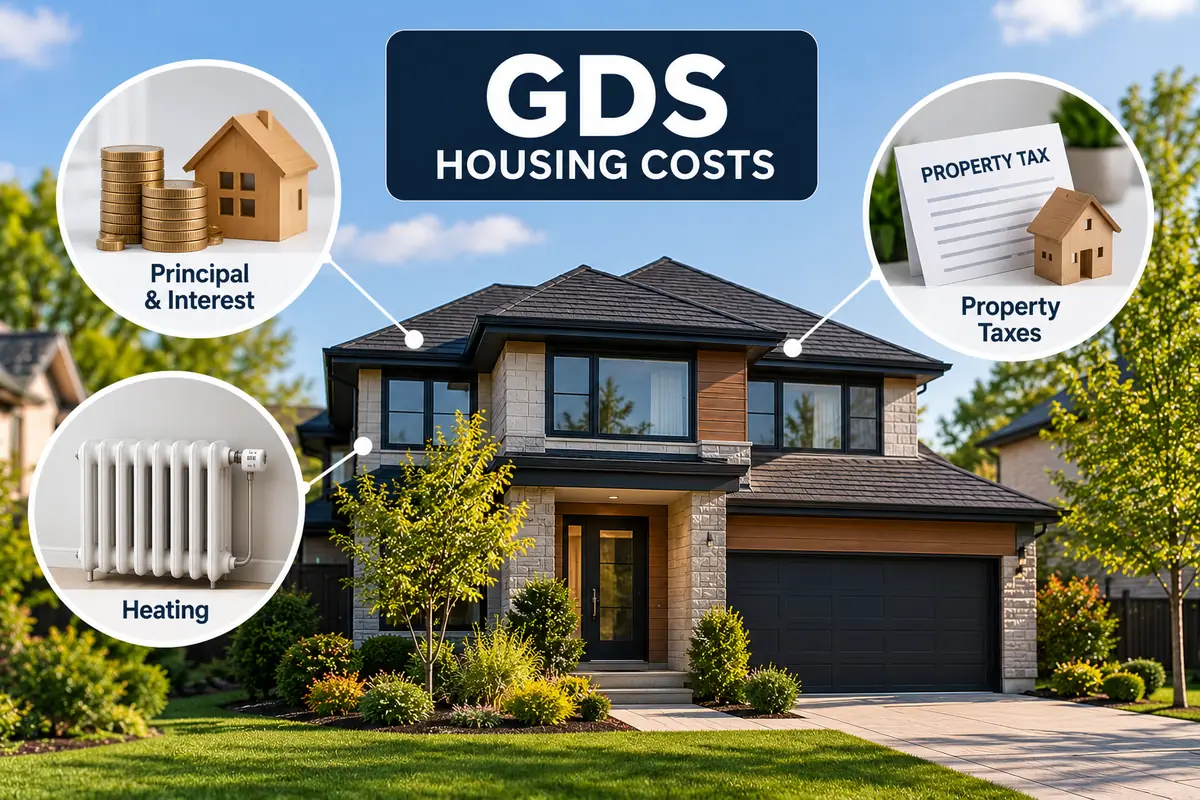
This assessment includes mortgage debt-service ratio calculations, while the amount available to borrow can also be constrained by the property’s loan-to-value ratio.
What if you’re refinancing a rental property?
Refinancing means qualifying again under the new lender’s requirements. A lender may review current leases, rental income, property value, existing debt and your personal finances.
If a tenant leaves and the next lease is signed at a lower rent, the refinance calculation may change. But an advertised market decline does not automatically reduce income from an existing lease.
Before counting on equity from a rental property, ask your mortgage agent to assess the lender’s treatment of the actual and projected rent. The terms of refinancing an existing mortgage also depend on the property’s value and your ability to qualify.
Could lower rents create a buying opportunity?
Lower rents are not automatically bad news for a buyer if property prices have fallen further. What matters is the relationship between purchase price, achievable rent and ongoing costs.
Assumption — illustrative example: At $500,000 and $2,500 monthly rent, gross annual rental yield is 6.0%. At $450,000 and $2,400 monthly rent, it is 6.4%. These are hypothetical numbers, not current market listings.
Neither figure is net cash flow. Property taxes, insurance, repairs, vacancies, management, condominium fees and mortgage payments can substantially change the result. The decision about when to enter the housing market should therefore consider both purchase price and carrying costs.
Why condo investors should pay attention
The report indicates national advertised condominium rents fell 7.8% year over year, compared with 2.7% for purpose-built apartments. This is a difference in advertised rents, not proof of a difference in investment profitability.
Condominium owners still need to budget for mortgage payments, maintenance fees, property taxes, insurance and unexpected assessments. Compare realistic current rents with the property’s full monthly carrying costs. The monthly payment itself can differ significantly under 25-year and 30-year amortization scenarios, subject to mortgage eligibility.
Can basement-apartment income help you qualify?
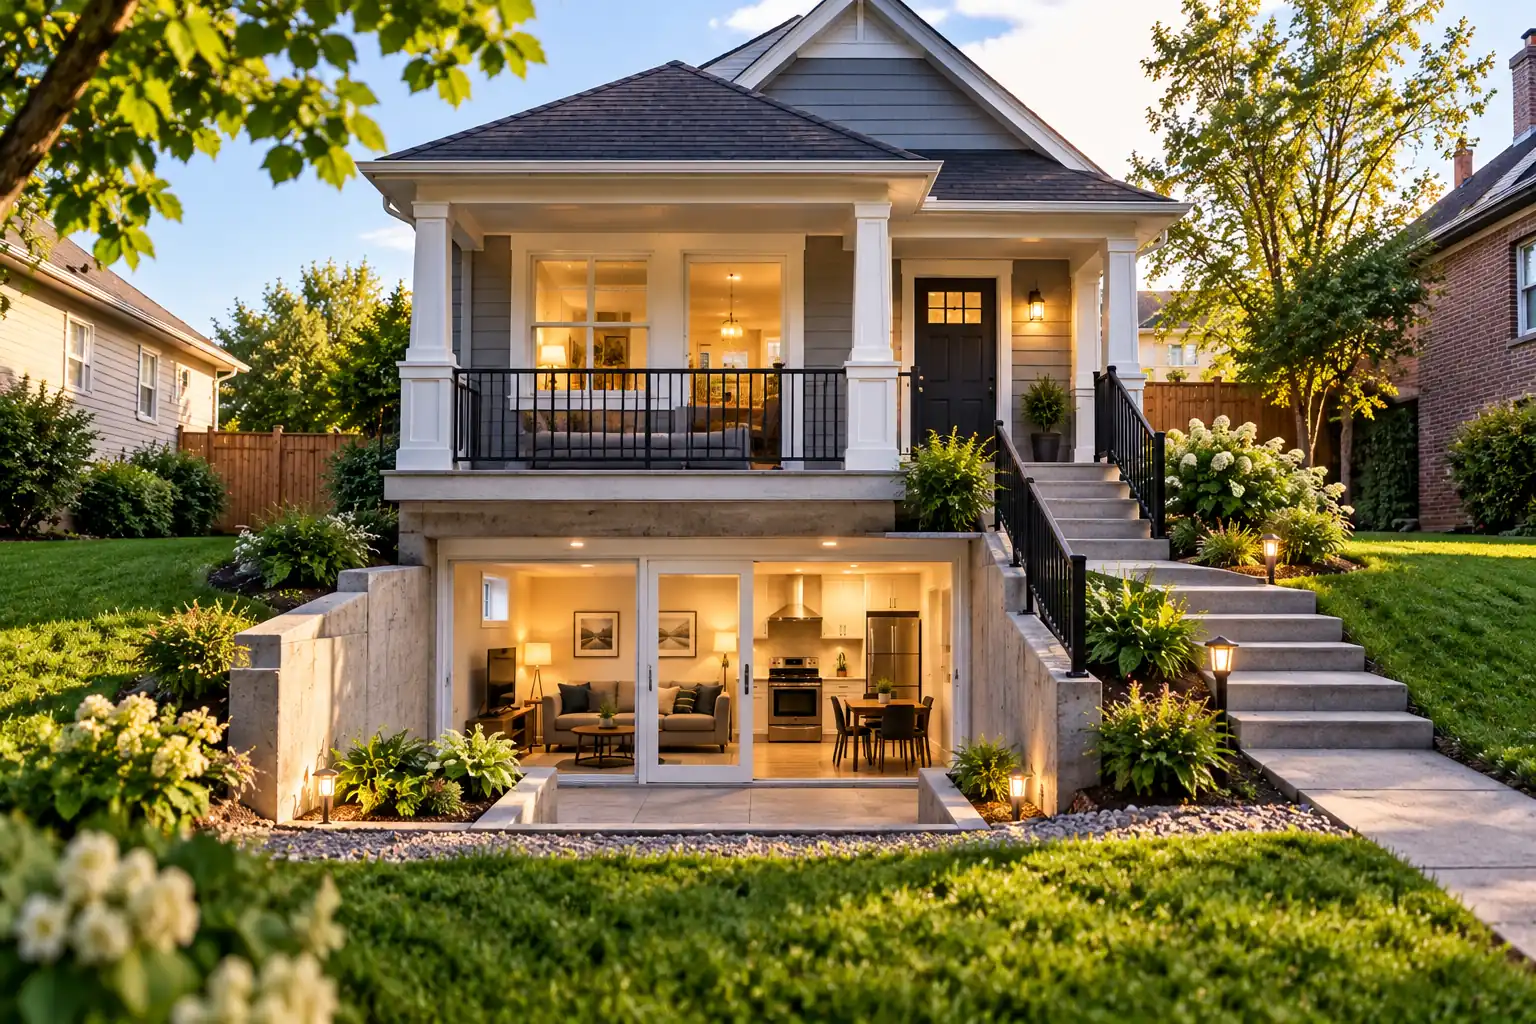
A secondary suite can contribute to mortgage qualification, including when purchasing an owner-occupied home with a basement apartment. For a qualifying two-unit owner-occupied property under CMHC rules, up to 100% of gross rental income can be used in the prescribed approach. That does not mean every lender will automatically count all projected rent; the property, documentation and lender policy still matter.
Lenders may examine the suite’s legal status, appraisal, lease and rental history. Where a unit is vacant or newly created, the lender may rely on an appraiser’s market-rent opinion rather than the rent a borrower hopes to charge. Do not assume that a national asking-rent average—or all projected rent—will be accepted for qualification.
The portion of rent a lender recognizes can influence mortgage debt-service ratio calculations and ultimately the amount you qualify to borrow.
Should you wait for rents to recover?
National rent averages cannot predict the rent for a specific street, building or unit. Nor can they tell us when a local rental market will recover.
Before buying or refinancing, stress-test the property against a lower achievable rent, a vacancy and higher expenses. The important question is whether the financing remains manageable even if conditions do not improve quickly, especially when choosing mortgage strategies under uncertain rates.
Sources: Rentals.ca and Urbanation National Rent Report and CMHC rental-income guidance. Lending requirements vary by lender, borrower, property and mortgage-insurance program.
About the author: Jason Wodlinger is an Ontario Mortgage Agent Level 2. This article explains general rental-income qualification concepts; the amount of rent a lender recognizes depends on the specific lender, property, documentation and mortgage program.