A larger mortgage approval could help some Ontario buyers enter the market sooner, but it could also leave them paying more for a home.
What Are the Banks Proposing?
On November 10, 2026, the National Housing and Investment Initiative (NHII), involving major banks and homebuilders, released its original housing-policy report (Recommendations 17–18) for Ottawa. It proposes down-payment assistance, more flexible mortgage qualification and a possible capped mortgage-interest deduction or tax credit for certain newly built homes. These are industry recommendations, not changes to mortgage or tax law.
Some measures are designed for newly built homes rather than ordinary resale properties. Other recommendations address developer financing and faster approvals to encourage construction. The eligibility rules, financing terms and implementation dates are not established.
Could Down-Payment Help Make Buying Easier?
Under current federal down-payment rules, qualifying homes priced below $1.5 million generally require 5% of the first $500,000 and 10% of the portion above that amount. Assumption: For a $600,000 newly built home, the minimum is $35,000, before closing costs and any applicable insurance premium. The report suggests lower requirements or low-interest assistance loans, but no program terms are in force.
Even if a future loan helps someone assemble the down payment, additional debt may create another repayment obligation. Mortgage applicants must still meet lender requirements covering income, credit, existing debts and the property. It is unknown which types of assistance would qualify or how lenders would assess them.
Could the Stress Test Become Easier?
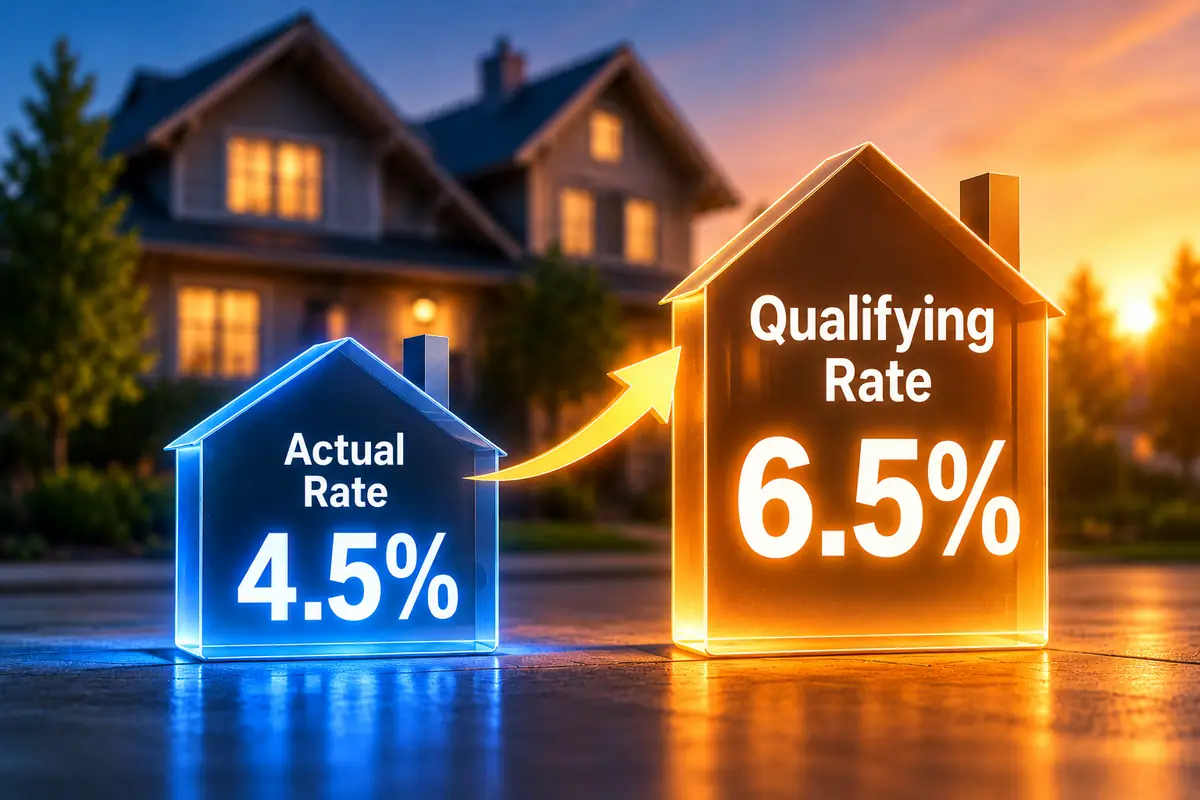
Today, most new uninsured mortgages at federally regulated lenders must qualify at the higher of 5.25% or the offered mortgage rate plus two percentage points, according to OSFI’s current rules. The industry recommends a sliding qualifying rate based on factors such as mortgage term or buyer type. No replacement formula or start date has been enacted.
A lower qualifying rate could produce larger approvals for some first-time buyers without changing the interest rate they actually pay. Borrowing more can still bring higher payments, greater interest costs and renewal risks. Lender approval does not establish household affordability; see our mortgage stress test guide.
Could Mortgage Interest Become Tax-Deductible?
Mortgage interest on a personal residence is generally not deductible under today’s rules, apart from qualifying income-earning uses explained by the Canada Revenue Agency. The initiative proposes allowing some younger or first-time buyers of newly constructed homes to deduct some mortgage interest. Who would qualify and how much tax they might save are not specified.
The suggested trade-off is a reduction in the principal-residence exemption when the owner later sells at a profit. Under current CRA guidance, a qualifying principal residence may receive a capital-gains exemption for all qualifying years. The proposed offset’s calculation and long-term tax consequences remain unverified; it should not be treated as an available deduction.
Could Easier Borrowing Raise Home Prices?
Easier credit may attract buyers to newly built housing and help builders move ahead with construction. But if purchasing power grows before additional homes are delivered, more competition could push prices higher. That is a risk, not a forecast, and restricting support to new homes would not eliminate it.
For Ontario buyers, a builder’s asking price, incentives and construction timeline may matter more than a possible future tax break. Compare the total ownership cost of new and resale properties, including closing expenses, insurance and any condo fees. Our guide to high-ratio mortgages explains the existing smaller-down-payment framework.
What Should Ontario Buyers Do Now?
Ask a lender to calculate your current qualifying amount and payment at the rate actually offered, not a proposed stress-test rate. Set a household budget that covers taxes, utilities, repairs, condo fees if applicable and cash remaining after closing. Review how your down payment affects the loan before increasing your purchase ceiling.
These proposals may eventually reduce upfront barriers, but they do not guarantee cheaper homes or a lower monthly payment. For now, eligibility, tax treatment and timing are unconfirmed. Do not rely on an industry proposal when setting a firm closing date or financing condition.